What Is Flexa? How the Crypto Payments Network and AMP Collateral Work in 2026
On this page
Flexa in one paragraph
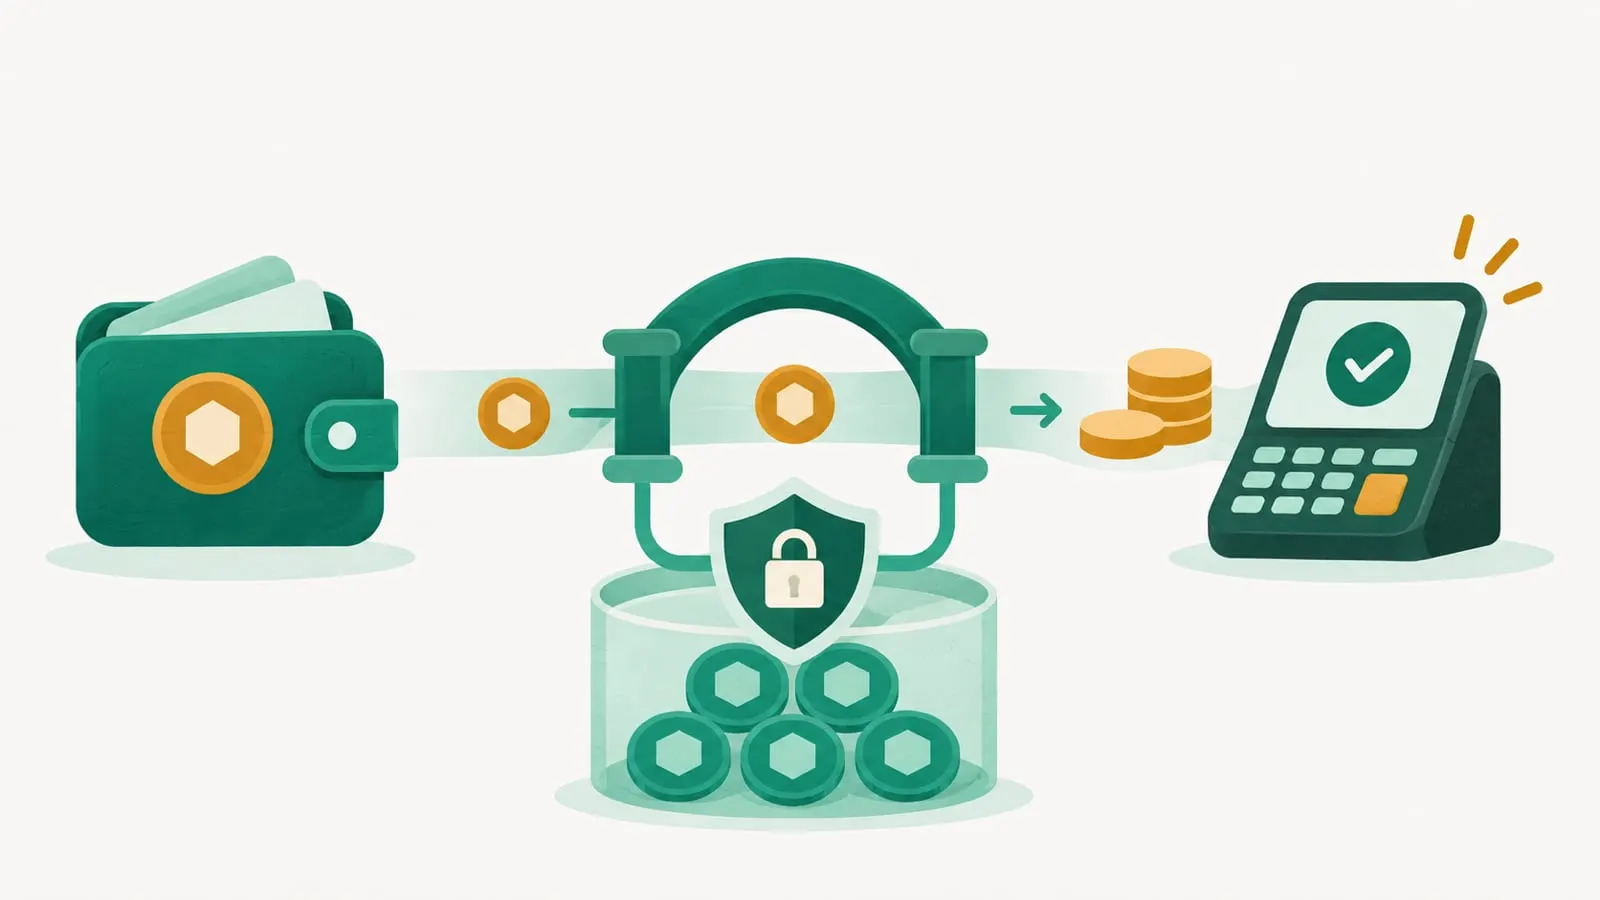
Flexa is a payments network that lets customers pay merchants with cryptocurrency and stablecoins while the merchant gets paid in ordinary money. A shopper pays from a Flexa-enabled wallet or app; Flexa guarantees the payment instantly using collateral held in a token called Amp (AMP), then completes the conversion and settlement in the background. The merchant never has to hold crypto or wait for blockchain confirmations, and Flexa says payments cannot be charged back.
This page explains how that model works, what AMP collateral does, what has changed since this article was first published in 2022, and the risks for anyone using or “staking” AMP. It is not a recommendation to buy AMP.
How a Flexa payment works
A traditional card payment passes your account details through several intermediaries and can be reversed weeks later. A Flexa payment works differently:
- You pay from an app. Flexa does not run its own consumer wallet. Payments start in a wallet or app that has integrated Flexa’s tools, called Components (SDKs for iOS, Android and React Native). Recent integrations Flexa has announced include Zashi and Nighthawk (Zcash wallets), Base Pay for USDC checkout, and “mini app” payments inside social wallets.
- Flexa locks collateral against the payment. Before the blockchain transaction is final, Flexa assigns collateral from an onchain pool to back it. Flexa claims transfers on Capacity complete in under 500 milliseconds.
- The merchant is paid. The merchant accepts the payment through Flexa at the register, online or in-app, and receives local currency. Flexa says it handles KYC and compliance on the merchant’s behalf and charges no fees for conversion or custody on payouts.
- The crypto transaction settles. Once the underlying digital currency transfer confirms on its chain, the collateral is released for the next payment. If a payment were to fail or be double-spent, the collateral is what covers the loss.
That last step is the core idea. Blockchains are slow for retail by card standards: Bitcoin blocks arrive roughly every ten minutes, and even fast chains need a few seconds. Collateral turns a payment that is pending into one the merchant can treat as final immediately, which is what a checkout queue needs. For the background on why on-chain payments cannot be reversed, see why smart contract transactions are irreversible.
What AMP is and why Flexa uses it
AMP is an ERC-20 token on Ethereum that Flexa launched in 2020 (its contracts were audited by Consensys Diligence) specifically for collateralization. Flexa describes it as a neutral, fixed-supply asset reserved for collateral use. The token contract supports “collateral partitions”, which let balances be earmarked for a particular application or pool while staying in the holder’s control.
Two practical points:
- Customers do not pay in AMP. Shoppers pay with whichever supported asset they hold (Flexa lists 99+ assets, including major coins and stablecoins). AMP sits behind the scenes as the guarantee.
- Stewardship moved away from Flexa. Flexa says it completed the transfer of Amp ecosystem stewardship to an independent organization, the Acronym Foundation, in 2023. The Anvil protocol, which now holds Flexa’s collateral, comes from that ecosystem.
Flexa Capacity: where the collateral comes from
Flexa Capacity is the network of onchain collateral pools that backs every payment. Each app or network Flexa supports has its own pool. Anyone can supply AMP to these pools, which is why some guides call it “staking AMP”, though it is really collateral provision.
How providers are rewarded, per Flexa’s documentation:
- Usage-based rewards. When Flexa uses a pool’s collateral to secure payments, providers in that pool earn AMP rewards in proportion to their share of the pool.
- Time-weighting. Since Capacity v3 (launched February 2025), rewards are paid monthly and weighted by how long collateral has been pooled, using first-in, first-out ordering, to stop large last-minute deposits from capturing rewards.
- Boosts. Selected pools can earn up to 2x rewards in a given month if collateral is deposited by a set date.
- Unlocks. In v3, withdrawing collateral takes between 12 and 24 hours after an unlock request, with the exact time shown when you request it.
Capacity v3 moved collateral from Flexa’s original FlexaCollateralManager contract into the Anvil vault, which Flexa says is independently audited. Flexa stopped using v2 collateral on June 30, 2025.
Flexa does not publish a fixed reward rate, and rewards depend on how much payment volume each pool secures. Treat any “AMP staking APY” figure you see elsewhere as a snapshot at best. Our guide to how DeFi staking works covers the general mechanics.
What has changed since 2022
| Date | Development |
|---|---|
| 2020 | AMP launched as Flexa’s collateral token; audited by Consensys Diligence |
| 2023 | Amp ecosystem stewardship transferred to the Acronym Foundation |
| 2024 | Flexa Components launched; Sheetz expanded in-store crypto payments with Flexa |
| Feb 2025 | Capacity v3 launched on the Anvil vault; Tap to Pay for NFC hardware wallets |
| Oct 2025 | Bealls added digital currency payments nationwide; Base Pay integration for USDC |
| Jun 2026 | Co-founder Trevor Filter named CEO (announced June 18), succeeding Daniel McCabe; chief legal officer Upneet Teji also became President; strategy refocused on “regulated money movement of crypto and stablecoins” |
| Jul 2026 | Euro settlement launched across the SEPA area through Flexa Polska |
Flexa’s licenses page lists 40 US jurisdictions where it holds licenses (38 states plus Washington, DC and Puerto Rico); the scope varies by state, and the page notes, for example, that its Tennessee money transmitter license does not cover virtual currency transmission. For most other jurisdictions it names only the regulator, so it does not say which of the 40 licenses cover virtual currency transmission. Its European announcement says the Warsaw subsidiary was formed in anticipation of the EU’s MiCA rules; it does not claim a MiCA license. The older version of this page also said Flexa aimed to make its network net-zero within three years; we could not find a current commitment or progress report, so we have left it out.
Benefits, and who they are really for
Most of Flexa’s advantages accrue to merchants:
- No chargebacks. Card disputes are a major cost for retailers. Crypto payments cannot be pulled back by the payer, and Flexa’s collateral guarantees the merchant is paid.
- Fast confirmation at the point of sale. Merchants do not wait for block confirmations.
- No crypto handling. Merchants receive local currency and do not need wallets or custody arrangements.
For customers, the benefits are narrower:
- You can spend crypto or stablecoins directly from a self-custody crypto wallet without first selling on an exchange.
- Flexa says payments do not pass your bank or card details to the merchant, which limits data exposure.
- The flip side of “no chargebacks” is that you lose card-style buyer protection. If there is a problem with an order, you depend on the merchant’s refund policy.
- Spending crypto can be a taxable disposal in many countries, just like selling it.
Risks
For shoppers:
- No buyer protection as with a credit card, and payments are final once made.
- App risk. You rely on the wallet app you pay from; check that it is the official app and keep it updated.
- Tax. Each crypto payment may create a capital gain or loss that you need to record.
For AMP collateral providers:
- Token price risk. AMP traded around $0.0005 in mid-November 2026 per CoinGecko, with a market cap near $48 million, against an all-time high of about $0.12 in June 2021. Rewards are paid in AMP, so a falling price can outweigh them.
- Collateral loss. Flexa warns that pooling carries inherent risk and that you should “only ever provide collateral you can afford to lose.” If an app or network a pool backs is compromised, that pool’s collateral is exposed.
- Smart-contract risk. Collateral sits in the Anvil vault and related contracts. Audits reduce but do not remove smart contract vulnerabilities.
- Liquidity and lockups. Unlocks take 12 to 24 hours, so you cannot exit instantly in a market drop.
- Concentration risk. Reward volume depends on one company’s payment business, its partners and its regulatory standing.
Earning a token reward for locking capital is not a savings account with deposit protection. For a broader look at evaluating yield, see the risks of yield farming.
How Flexa compares with other ways to pay in crypto
| Approach | How the merchant is paid | Main trade-off |
|---|---|---|
| Flexa | Local currency, guaranteed instantly by AMP collateral | Depends on Flexa-enabled apps and Flexa’s merchant network |
| Crypto debit cards | Card networks pay merchants; the card provider sells your crypto | Custodial; card fees and KYC; works almost anywhere cards do |
| Direct stablecoin payments | Merchant receives stablecoins on-chain | Merchant must handle wallets, accounting and conversion |
| Lightning Network (Bitcoin) | Merchant or processor receives BTC instantly | Requires Lightning-capable wallets on both sides, or a payment processor |
If your goal is everyday spending, a stablecoin avoids price swings between buying and paying; see how to use stablecoins. For more on crypto as money, browse the DeFi basics guide.
Bottom line
Flexa solves a real problem for merchants: accepting crypto with instant, final settlement and no crypto on the balance sheet. It does this by backing each payment with AMP collateral supplied by the public. The payments business has kept expanding into 2026, with new merchants, wallets and European settlement. AMP, the token that secures it, has lost almost all of its peak value, which shows that a network can grow while its token does not. If you use Flexa to pay, treat payments as final. If you supply collateral, size it as money you could lose.
Frequently asked questions
Is Flexa a wallet?
No. Flexa is a payment network and set of tools. You pay from a wallet or app that has integrated Flexa, and the merchant accepts the payment through Flexa at its point of sale or checkout.
What is AMP used for?
AMP is the collateral token for Flexa. Collateral in Flexa Capacity pools guarantees each payment while the underlying transaction settles on its blockchain. If something goes wrong, the collateral is meant to cover the merchant.
How do you earn rewards with Flexa?
By depositing AMP into a Flexa Capacity pool. Flexa pays AMP rewards to providers in proportion to their share of a pool when that pool's collateral is used, weighted by how long the collateral has been pooled. Rewards are variable and paid in a volatile token.
Which stores accept Flexa?
Flexa has announced merchants including Sheetz convenience stores and Bealls department stores. Acceptance changes, so check the Flexa-enabled wallet you use for its current merchant directory.
Is Flexa regulated?
Flexa's licenses page lists 40 US jurisdictions (38 states plus Washington, DC and Puerto Rico) where it is licensed, though it does not say which licenses cover virtual currency transmission (its Tennessee license does not), and it is registered with FinCEN as a money services business. In July 2026 it announced euro settlement across the SEPA area through a Warsaw-based subsidiary, but it had not announced MiCA authorization at the time of writing.
Sources
- Flexa: Capacity (collateral network)
- Flexa newsroom: Introducing Flexa Capacity v3 (February 2025)
- Flexa newsroom: Leadership transition (June 2026)
- Flexa newsroom: Flexa is now live across Europe (July 2026)
- Flexa newsroom (merchant and wallet announcements)
- Consensys Diligence: Amp token and Flexa collateral manager audit (2020)
- Flexa: US licenses
- CoinGecko: Amp (AMP) market data
Educational content, not financial advice. DeFi carries risk, including total loss of funds.