Aave vs Compound: How the Two DeFi Lending Protocols Compare in 2026
On this page
Aave vs Compound: the short answer
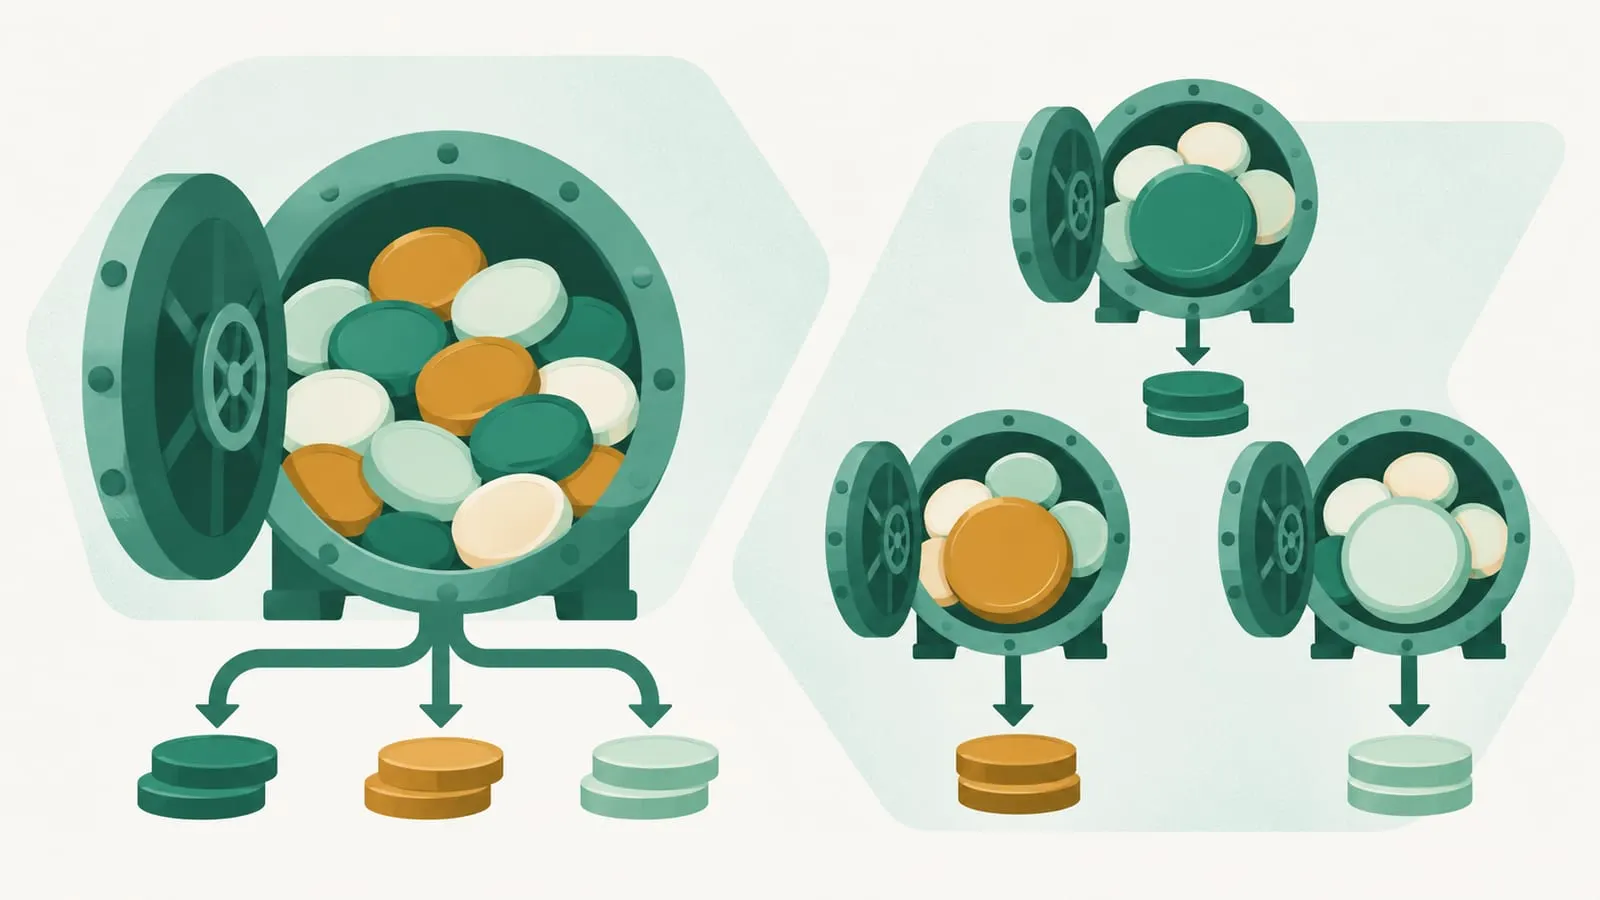
Aave and Compound are two of the longest-running DeFi lending protocols on Ethereum. Both let you supply crypto to earn interest and borrow against collateral, with rates set by supply and demand rather than by a lender. The key difference is structure: Aave is a broad, multi-asset money market where most supplied assets earn interest and can be borrowed, while Compound III splits lending into separate markets that each lend just one “base” asset (such as USDC), with collateral that earns nothing.
In practice Aave is much bigger, runs on more networks and has more features. As of mid-November 2026, DefiLlama shows roughly $14 billion in Aave V3 alone versus about $1 billion in Compound III. Compound III is the simpler, more conservative design. Check DefiLlama for live figures, because these numbers change daily.
Aave vs Compound at a glance
| Aave | Compound | |
|---|---|---|
| Current versions | Aave V3 (V3.7) on many chains; Aave V4 live since March 30, 2026 | Compound III (“Comet”); Compound V2 is being wound down |
| Market design | V3: one shared pool per network. V4: liquidity hubs feeding separate “spokes” | One isolated market per base asset (e.g. USDC, WETH, USDT) |
| What you can borrow | Many assets in the same position | Only the market’s base asset |
| Does collateral earn interest? | Yes, supplied assets earn the supply rate | No, only base-asset suppliers earn interest |
| Rate model | Variable rates on a utilization curve per asset (stable-rate borrowing was removed in V3.2); V4 adds a per-user risk premium | Variable rates on separate supply and borrow utilization curves for the base asset |
| What you hold after supplying | An interest-bearing aToken (e.g. aUSDC) | A balance inside the Comet market; no cTokens (those were Compound V2) |
| Liquidations | Liquidators repay debt and receive collateral plus a bonus | Protocol “absorbs” the account, then sells collateral at a discount |
| Flash loans | Yes | No native flash loans |
| Native stablecoin | GHO | None |
| Bad-debt backstop | Umbrella stakers, per asset (the DAO treasury has covered past shortfalls) | Each market’s protocol reserves absorb liquidated debt |
| Governance token | AAVE | COMP |
| Main networks | V3 on roughly 20 networks; V4 on Ethereum, Avalanche, Arc and Base | Ethereum plus L2s such as Arbitrum, Base and Optimism; several smaller deployments being retired |
How Aave works
Aave is a pool-based money market. You supply an asset, receive an interest-bearing aToken (for example aUSDC), and can use eligible assets as collateral to borrow others. All loans are overcollateralized, and borrowing is at a variable rate.
Aave V3
Aave V3 is still where most of Aave’s deposits sit. Each network has a pool of reserves, and each reserve has its own loan-to-value (LTV), liquidation threshold and liquidation bonus. Key features:
- E-Mode gives higher LTVs when you borrow and supply within a category of correlated assets, such as USD stablecoins or ETH and liquid staking tokens. Since V3.7 (rolled out April-May 2026), categories can be “isolated” so only that category’s collateral counts.
- Isolation Mode and Siloed Borrowing were removed in V3.7 and replaced by isolated E-Mode categories. Some deployments still run V3.6, where they remain.
- Flash loans let developers borrow without collateral as long as the loan is repaid within the same transaction. They are a tool for arbitrage, refinancing and liquidations, not a way for beginners to get capital.
- GHO is Aave’s own overcollateralized stablecoin, minted by borrowers against their collateral.
Aave V4: hubs and spokes
Aave V4 launched on Ethereum mainnet on March 30, 2026, then on Avalanche (July 2026), Circle’s Arc chain (September 2026) and Base (October 2026), according to Aave’s changelog. It replaces the single pool with a hub-and-spoke model:
- A Liquidity Hub holds the shared liquidity and gives each spoke a credit line, capping how much any one market can draw.
- Spokes are the markets users interact with, each with its own risk parameters, oracles and emergency stops. Ethereum launched with three hubs (Core, Prime and Plus) and eleven spokes according to Aave’s changelog (LlamaRisk’s activation review counted ten, leaving out supply-only tokenized spokes), including dedicated looping spokes for Lido’s wstETH and EtherFi’s weETH.
- A user risk premium is added on top of the shared borrow rate, based on the quality of the collateral backing your debt, so riskier collateral pays more.
In March and April 2026 Aave’s DAO backed the “Aave Will Win” framework, which ratifies V4 as the protocol’s long-term technical base and is meant to send revenue from Aave-branded products to the DAO treasury in exchange for funding Aave Labs. The binding April vote approved the Aave Labs funding; other parts were left to separate proposals. We found no announced shutdown date for V3.
How Compound works
Compound pioneered pooled lending with V1 (2018) and V2 (2019). Its current design, Compound III (codename Comet), went live on Ethereum in late August 2022 with a single USDC market. Compound V2 is being wound down: new borrows and mints are paused while repayments, withdrawals and liquidations continue.
Each Comet market is self-contained:
- There is one base asset you can borrow and supply for yield, such as USDC, USDT or WETH.
- Other assets are collateral only. They cannot be borrowed and earn no interest.
- Each collateral asset has a borrow collateral factor (how much you can borrow against it) and a higher liquidation collateral factor (when you become liquidatable), which gives a buffer between the two.
- Each collateral asset also has a supply cap, and the first borrow must meet a minimum size.
This design means a bad collateral asset in one market cannot directly drain another market, and suppliers of the base asset are only exposed to the collateral listed in that market. The trade-off is less flexibility: if you want to borrow ETH and USDC at once, you need positions in two markets. See what you need to borrow crypto with Compound for the step-by-step basics.
How interest rates work in each
Both protocols use utilization-based rates: utilization is the share of supplied funds currently borrowed. Rates rise slowly up to a target “kink” (Aave calls it the optimal usage ratio) and then steeply above it, which pulls in new supply and discourages borrowing when liquidity runs low.
- Aave: each asset has one borrow-rate curve. Supply rates are derived from what borrowers pay, minus the protocol’s reserve factor. In V4, your personal borrow rate also includes the user risk premium.
- Compound III: the base asset has two separate curves, one for suppliers and one for borrowers, each set by governance. Interest accrues every second.
Neither protocol is consistently cheaper. Rates depend on the asset, the chain and the moment, and can move sharply within hours. Compare the live APY in each app before acting. Some markets also pay token incentives, which can change without notice.
How collateral and liquidations work
Both protocols liquidate positions that become undercollateralized, but the mechanics differ.
Aave. Your health factor is the value of your collateral (weighted by each asset’s liquidation threshold) divided by your debt. Below 1, a liquidator can repay part of your debt and take collateral plus a liquidation bonus. On V3, a single liquidation can repay up to 50% of the debt, or up to 100% when the health factor is at or below 0.95 or when the borrower’s balance of the specific collateral or debt asset being liquidated is worth less than $2,000, a per-asset test rather than the whole position (see how lending works on Aave for the full rule). V4 changes this: liquidators repay only enough to bring the position back to a target health factor, the bonus grows as the position gets riskier, and leftover balances under $1,000 must be cleared in full to avoid dust.
Compound III. When your borrowing exceeds the liquidation collateral factors, anyone can call absorb. The protocol takes over your debt and collateral, credits you the collateral’s value minus a liquidation penalty, and later sells the seized collateral at a discount through buyCollateral while its reserves are below target. You end up with no debt, usually a small base-asset balance, and no collateral.
In both cases a liquidation costs you a penalty. Keep a buffer well above the threshold, especially with volatile collateral.
Governance tokens: AAVE vs COMP
Both protocols are governed on-chain by token holders through their DAOs. They vote on listings, risk parameters, deployments and treasury spending, usually guided by paid risk providers. Learn more about governance tokens.
- AAVE is used for voting and can be staked in Aave’s legacy Safety Module (stkAAVE). Aave’s Umbrella system (June 2025) lets users stake aTokens to cover bad debt in specific markets in exchange for rewards, at the risk of being slashed. After a 2025 governance decision, stkAAVE’s maximum slashing is set to 0% (as read on-chain in November 2026), so staked AAVE no longer backstops bad debt. A months-long dispute between Aave Labs and DAO delegates over revenue from Aave-branded products led to the “Aave Will Win” framework, approved in stages in March and April 2026.
- COMP holders vote through Compound Governor. COMP is also distributed as rewards in some markets. Compound governance has been contentious: in July 2024 a whale-led group narrowly passed Proposal 289 to move about 499,000 treasury COMP (roughly $24 million at the time) into a vault it would control, then cancelled it days later in exchange for a planned COMP staking product. In September 2026 a delegate alleged that about 8.4 million DAI of DAO reserves from deprecated Compound V2 markets had been converted into COMP whose votes were delegated to the Compound Foundation; the Foundation replied that the COMP sits in a DAO-owned multisig and was not spent on its own operations. The dispute had not been resolved through a governance vote on Compound’s forum or Tally as of mid-November 2026.
Security track record
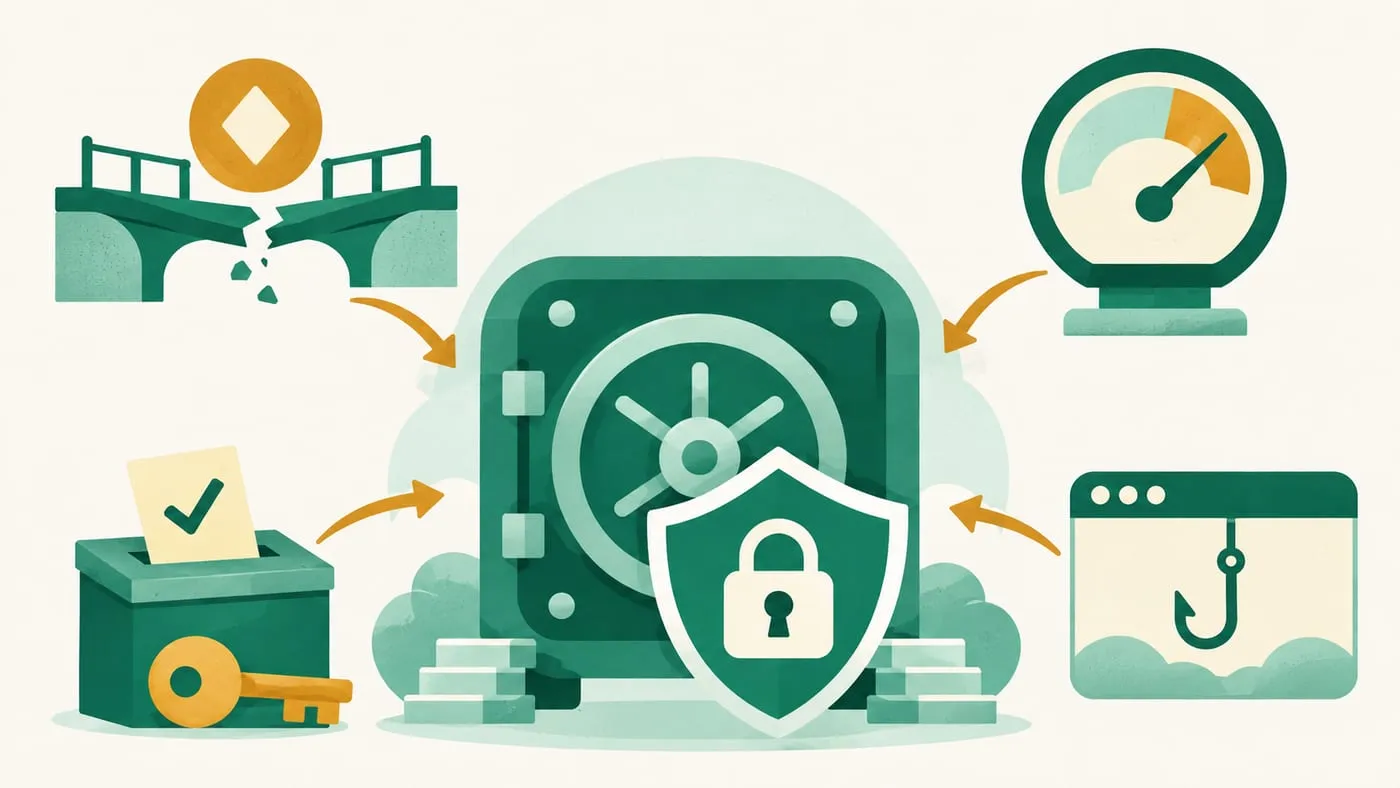
To our knowledge, no exploit of either protocol’s core lending contracts has drained user deposits. Both have still had serious incidents, mostly from collateral assets, oracles, governance or websites:
Aave
- March 2026: a misconfigured price-cap (CAPO) oracle on the Ethereum Core and Prime markets undervalued wstETH by roughly 2.85%, triggering around $26 million of liquidations. No bad debt was reported. A governance proposal to reimburse affected users from the DAO treasury was executed in late March 2026, and the forum thread records the funds as distributed by early April; after partial recoveries from block builders and searchers, the net cost to the DAO was about 317 WETH.
- April 2026: an attacker exploited a Kelp rsETH bridge route, released unbacked rsETH, and used it as collateral on Aave V3 to borrow roughly 82,650 WETH. Aave’s incident report first modeled bad debt between roughly $124 million and $230 million, depending on how Kelp allocates losses; an April 22 update from risk provider LlamaRisk revised that to about $62 million to $162 million, and no final figure had been published on Aave’s forum by mid-November 2026. The report found Aave’s contracts were not compromised. rsETH and several WETH markets were frozen.
- November 2022: a large leveraged short of CRV on Aave V2 was liquidated as the CRV price rose, leaving roughly $1.6 million of bad debt (about 2.7 million CRV), which the DAO later covered. Aave froze several V2 markets afterwards.
Compound
- September 2021: a bug introduced by a governance upgrade (Proposal 62) let some users claim far more COMP rewards than intended; up to about 280,000 COMP was at risk. Later proposals paused and fixed distribution, and some COMP was returned. User deposits were not affected.
- July 2024 and March 2026: the compound.finance website was hijacked and redirected users to phishing pages. No smart contracts were affected, and no losses were reported in 2026.
- November 2025: on risk manager Gauntlet’s recommendation, withdrawals and new borrows were temporarily paused on Ethereum’s USDC, USDS and USDT Comets after the deUSD/sdeUSD collateral lost its peg. The USDC and USDS markets were unpaused two days later once risk parameters changed, and on-chain records show the USDT market’s withdrawals unpaused on November 7, 2025; it was operating normally in November 2026.
- 2026: governance has been retiring lightly used Comets, including the Linea markets and Mantle USDe market (June 2026) and the Polygon and Unichain markets (July 2026), so check that a market is still active before you deposit.
Which suits whom?
- You want to borrow several assets from one position, use E-Mode for stablecoin or ETH loops, or need flash loans: Aave’s design fits better.
- You want your collateral to keep earning yield while you borrow: Aave, since Compound III collateral earns nothing.
- You mainly want to borrow USDC or another single asset against blue-chip collateral, and value isolated markets: Compound III’s model is simpler to reason about.
- You are a passive stablecoin lender: both work. Compare the live supply rate, utilization (high utilization can delay withdrawals) and the collateral that backs each market.
- You use a particular network: Aave covers far more chains. Confirm the specific market exists and isn’t being deprecated.
For a wider field, see our guide to the best crypto lending platforms or the Lending & Borrowing hub.
Risks to understand before using either
- Liquidation risk: a sharp price drop or an oracle error can liquidate you and cost you a penalty.
- Collateral and bridge risk: as the rsETH incident showed, a failure in one listed asset can cause bad debt for lenders in the same market. Wrapped or bridged tokens such as wrapped bitcoin add the issuer’s or bridge’s risk on top.
- Liquidity risk: at 100% utilization, suppliers may not be able to withdraw until borrowers repay or new supply arrives.
- Smart contract and governance risk: audits reduce but don’t remove bugs, and token-holder votes can change parameters that affect you.
- Front-end risk: bookmark the official app URLs and check transactions in your wallet before signing.
See DeFi lending risks for more detail. This page explains how the protocols work and is not financial advice.
Frequently asked questions
Is Aave better than Compound?
Neither is better for everyone. Aave offers more assets, more chains and more features; Compound III offers a narrower, simpler design where each market lends a single asset. The right fit depends on what you want to borrow, on which chain, and how much complexity you want to manage.
Does collateral earn interest on Compound?
Not on Compound III. Only suppliers of a market's base asset (for example USDC in the USDC market) earn interest; collateral assets neither earn nor pay interest. On Aave, supplied assets earn the supply rate whether or not they are used as collateral.
Does Compound offer flash loans?
Compound III has no native flash loan function. Aave supports flash loans, which must be borrowed and repaid within a single transaction.
What is the health factor on Aave?
It is the value of your eligible collateral (adjusted by liquidation thresholds) divided by your debt. If it falls below 1, your position can be liquidated.
Does Aave or Compound require KYC?
The core protocols are permissionless smart contracts and do not require KYC to supply or borrow. Exceptions exist: in Aave's Horizon real-world-asset market, only allowlisted qualified users can supply the tokenized collateral (anyone can supply stablecoins), and front ends may block certain regions or addresses. Neither protocol runs a credit check.
Can I use Bitcoin as collateral on Aave or Compound?
Not native BTC. Both accept tokenized or wrapped bitcoin (such as WBTC or cbBTC) on some markets, which adds the custodian or bridge risk of that token on top of the lending protocol's own risks.
Is Aave V3 being shut down now that V4 is live?
We found no announced shutdown date as of November 2026. V3 is still being upgraded (V3.7 rolled out in April-May 2026) and holds most of Aave's deposits, although Aave's governance has endorsed V4 as the long-term base.
Sources
- Etherscan: Compound III USDT Comet (unpause transaction, November 7, 2025)
- Compound community forum: Statement on the use of V2 reserves (Compound Foundation, September 2026)
- Compound community forum: Misappropriation of the v2 DAI reserves by the Compound Foundation (September 2026)
- Aave governance forum: LlamaRisk update to the rsETH incident report (April 22, 2026)
- Aave governance forum: [Direct to AIP] wstETH CAPO Oracle Incident User Reimbursement
- Aave governance forum: [ARFC] Aave V4 Activation on Ethereum Mainnet (LlamaRisk review)
- Etherscan: stkAAVE contract (getMaxSlashablePercentage)
- Aave governance forum: [ARFC] Safety Module & Umbrella Emission Update (stkAAVE slashing to 0%)
- Aave V3 source code (aave-dao/aave-v3-origin): LiquidationLogic.sol
- Aave documentation: Aave V4 overview
- Aave documentation: Aave V3 overview
- Aave documentation: Changelog
- Aave governance forum: rsETH Incident Report (April 20, 2026)
- Compound III documentation: Liquidation (absorb and buyCollateral)
- Compound community forum: Gauntlet, Pausing Ethereum USDC, USDS and USDT Comets
- Compound III documentation: Collateral and borrowing
- DefiLlama: Aave and Compound protocol data
Educational content, not financial advice. DeFi carries risk, including total loss of funds.