What Determines Interest Rates on Crypto Lending Platforms?
On this page
- The short answer
- Factor 1: Utilization and the rate curve
- Factor 2: The reserve factor and the supply–borrow spread
- Factor 3: Governance and risk managers
- Factor 4: Demand for leverage
- Factor 5: Off-chain interest rates
- Factor 6: Risk and collateral
- Factor 7: Token incentives
- Why DeFi and CeFi rates differ
- Fixed vs variable rates
- What this means for you
- Risks to keep in mind
I want to borrow crypto without collateral, and I decided to start by looking at the prices of various crypto coins between the different platforms, including the interest rates on lending platforms. However, I don't understand how and why they can vary so much?
The short answer
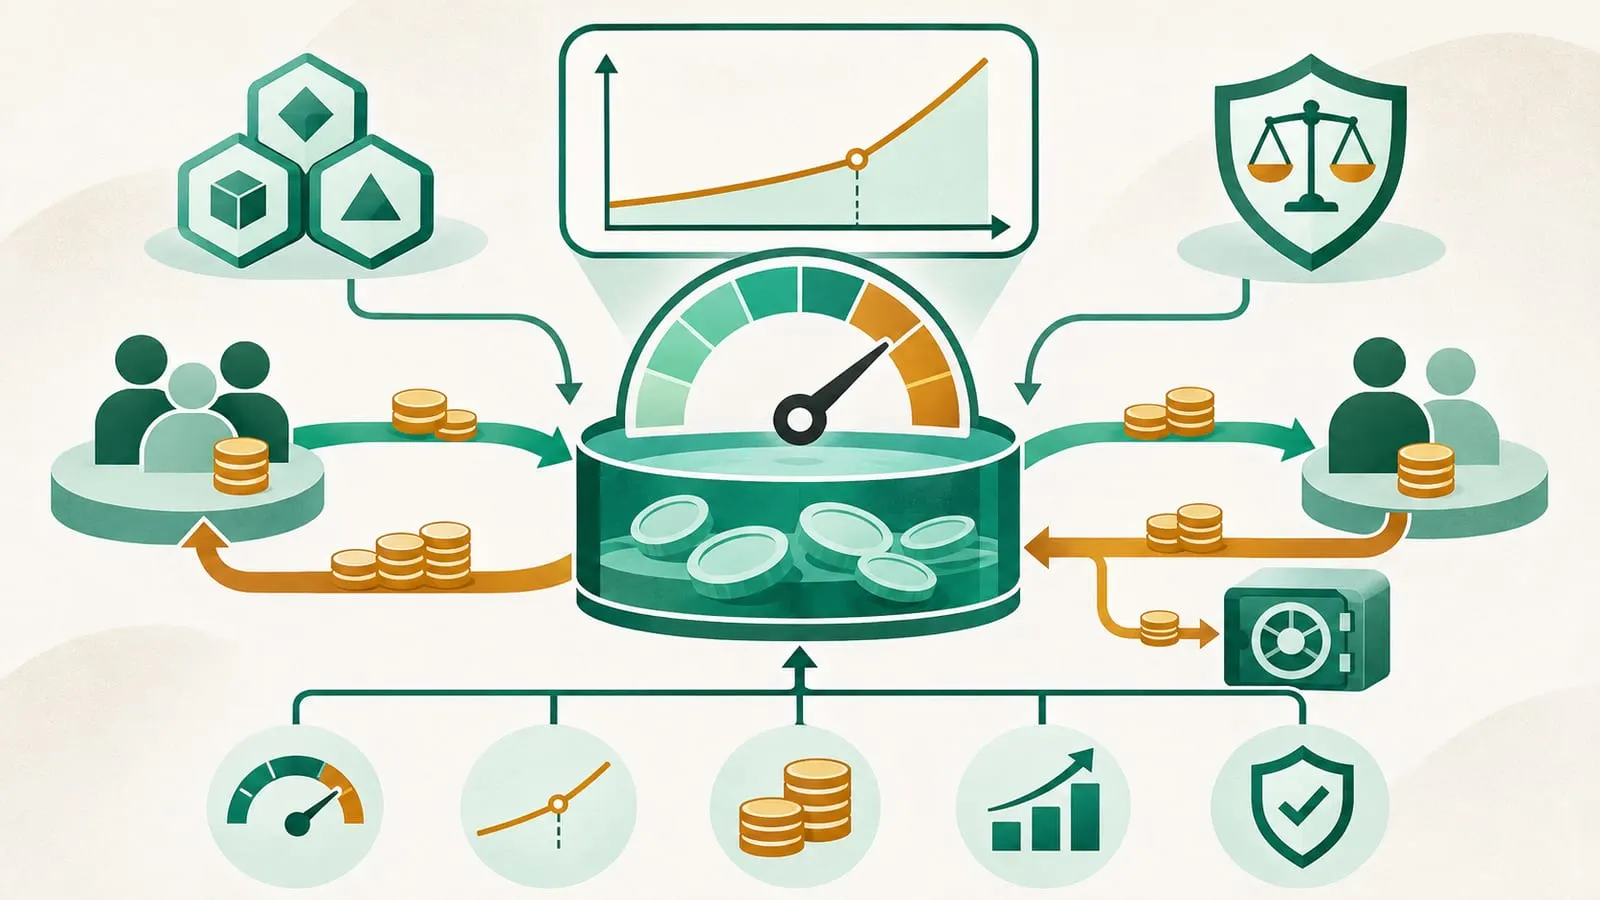
On decentralized lending platforms, interest rates are set by code, not by a bank or a loan officer. Each asset’s pool has a formula that sets the rate from utilization, the share of deposits currently borrowed. When borrowing demand rises, utilization rises, and the formula raises rates to attract lenders and discourage borrowers. When demand falls, rates fall.
Behind that formula sit a few deeper forces: how much people want leverage, what the same dollars could earn elsewhere, the risk of the collateral in the pool, the protocol’s cut and any token rewards. Centralized lenders are different: they set rates themselves. The sections below explain each factor and why rates vary so much between platforms. For the broader picture, see our interest rates and crypto lending hubs.
Factor 1: Utilization and the rate curve
Utilization = total borrowed ÷ total supplied. Protocols map utilization to a borrow rate with a kinked curve:
- Below the optimal point (the “kink”), the rate rises gently with utilization.
- Above it, the rate rises steeply. This protects lenders: if a pool nears 100% utilization, nobody can withdraw, so the protocol makes borrowing expensive enough that borrowers repay and lenders deposit.
Aave V3 describes its model as “two slopes with an optimal utilization point.” On Aave V3’s Core Ethereum market, USDC and USDT used a 94% optimal point as of a September 2026 risk update. Compound III goes a step further and uses separate supply and borrow curves, each with its own kink, both set by governance.
Newer designs adapt the curve automatically. Morpho’s AdaptiveCurveIRM targets 90% utilization and continuously shifts the whole curve up while utilization stays above target and down while it stays below, so rates drift toward a level that keeps the market near 90% without anyone voting on parameters.
Factor 2: The reserve factor and the supply–borrow spread
Lenders always earn less than borrowers pay, for two reasons:
- Only the borrowed part of the pool earns interest, but that interest is shared across all deposits.
- The protocol keeps a cut for its treasury or insurance fund. Aave calls this the reserve factor.
A useful approximation:
Supply rate ≈ borrow rate × utilization × (1 − reserve factor)
Worked example (real data, November 16, 2026, DefiLlama): Aave V3 Ethereum USDC had about $2.77 billion supplied and $2.62 billion borrowed, so utilization was about 94%. Borrowers paid about 5.2% APY and suppliers earned about 4.4%. The 0.8-point gap is the unborrowed slice plus the protocol’s share.
| Market (Ethereum) | Utilization | Borrow APY | Supply APY |
|---|---|---|---|
| Aave V3 USDC | ~94% | ~5.2% | ~4.4% |
| Aave V3 USDT | ~85% | ~4.1% | ~3.1% |
| Compound III USDC | ~90% | ~4.4% | ~3.4% |
| Aave V3 WETH | ~83% | ~2.0% | ~1.4% |
Rates are base rates from DefiLlama on November 16, 2026, before any token rewards. Check live data before acting.
Factor 3: Governance and risk managers
The curve’s shape is a policy choice. On Aave, independent risk firms acting as “risk stewards” propose and apply parameter changes within limits set by governance. In September 2026, for example, risk provider LlamaRisk posted a Risk Steward update raising the first slope for 15 stablecoin reserves from 4.10% to 4.30% and USDe’s base rate from 2% to 3%, part of a path that aims to price USDe borrowing in line with Ethena’s own staking rate. Changes like these shift every user’s rate overnight, without any change in demand.
Some systems set a rate directly. Sky (formerly MakerDAO) governance sets the Sky Savings Rate paid on sUSDS, and Aave’s DAO sets the savings rate paid on staked GHO (sGHO). These administered rates act as benchmarks: if lending USDC on Aave pays much less, capital tends to move.
Factor 4: Demand for leverage
Most crypto borrowing funds leverage or strategies: borrowing stablecoins against ETH or BTC to buy more, “looping” staked ETH against borrowed ETH, or borrowing stablecoins to farm higher yields elsewhere. So lending rates tend to rise in bull markets, when traders want leverage, and fall when the market cools. This is why stablecoin rates are usually higher than rates on BTC, which is mostly deposited as collateral and rarely borrowed, leaving its supply rate near 0%.
Factor 5: Off-chain interest rates
Crypto doesn’t exist in a vacuum. When US short-term rates are high, tokenized Treasury products and stablecoin savings products offer a competing lower-risk benchmark, and DeFi stablecoin lending tends to price above them to compensate for extra risk. In mid-November 2026 the Federal Reserve’s H.15 release showed the effective federal funds rate at about 3.9%, and the largest DeFi stablecoin markets paid suppliers roughly 3–4.5%. The link is loose, not mechanical.
Factor 6: Risk and collateral
Pools that accept riskier collateral, newer protocols and smaller chains usually pay lenders more, because fewer lenders will take the risk. A higher rate is often compensation for bad-debt, smart contract or liquidity risk, not free money. The same applies to borrowers: platforms set lower loan-to-value limits for volatile collateral. See collateralization and DeFi lending risks.
Factor 7: Token incentives
Protocols and token issuers sometimes pay extra rewards to suppliers or borrowers. These show up as a separate “reward APY” and can make a market look far better than its base rate. They end, and the reward token’s price can fall, so compare base rates when judging a market. Our guide to what is the best for yield farming covers how to read advertised yields.
Why DeFi and CeFi rates differ
Centralized lenders (exchanges and crypto lending apps) set rates at their discretion, based on what they can earn by re-lending or deploying your coins and how much they want to grow deposits. Their borrowing rates usually depend on terms you choose, such as the loan-to-value ratio and loan length, and some platforms offer lower rates to customers who hold or pay in the platform’s own token. Some centralized lenders once advertised stablecoin rates well above DeFi levels without clearly showing where the yield came from; Celsius, Voyager and BlockFi all filed for bankruptcy in 2022. A rate that isn’t explained by a visible mechanism is a warning sign. More in DeFi vs TradFi lending.
Fixed vs variable rates
Almost all DeFi lending rates are variable: they can change with every transaction that touches the pool. Aave removed its old “stable rate” option in V3.2 (October 2024). Fixed rates do exist through separate products, such as Pendle’s principal tokens and Morpho’s fixed-term Midnight markets. See fixed vs variable APR, and for converting between rate types, convert interest rate to APY.
What this means for you
- Lenders: compare base supply rates, utilization (very high utilization can delay withdrawals) and the collateral in the pool. See how to lend your crypto on DeFi.
- Borrowers: budget for rates to spike. A loan at 5% today can cost 15% next week if a market hits its kink. Watch your liquidation buffer as well as the rate.
- Without collateral: mainstream DeFi lending requires collateral; the exceptions are covered in crypto loans without collateral.
Risks to keep in mind
Variable rates can rise sharply with no warning, reward tokens can lose value, and a high advertised rate may reflect hidden risk. Lending deposits are not a savings account with deposit protection. This page explains how rates work and is not financial advice.
Frequently asked questions
How do crypto lending platforms calculate interest rates?
DeFi protocols such as Aave and Compound compute the borrow rate from the pool's utilization using a piecewise curve, then derive the supply rate from the borrow rate, utilization and reserve factor. Rates update with every transaction. Centralized platforms set rates at their own discretion.
What APR should I expect on a crypto loan?
On November 16, 2026, DefiLlama showed variable borrow rates of roughly 4–5.3% APY for USDC and USDT on the largest Ethereum markets of Aave V3 and Compound III, and about 2% for borrowing ETH on Aave V3. Rates can jump within hours if utilization spikes.
Why do interest rates differ so much between platforms?
Each platform has its own pool of lenders and borrowers, its own rate curve and reserve factor, different collateral and risk, and sometimes token rewards. Liquidity doesn't move instantly between platforms, so gaps persist.
Why does Bitcoin earn almost no interest on DeFi lending platforms?
Few people borrow BTC on these platforms; it is mostly posted as collateral to borrow stablecoins. With low utilization, the supply rate is close to zero.
Can I borrow crypto without collateral to avoid these rates?
Mainstream DeFi lending requires over-collateralization. The main exceptions are flash loans, which must be repaid in the same transaction, and permissioned credit platforms for vetted borrowers.
Sources
- Aave documentation: Aave V3 overview (interest rate model)
- Compound III documentation: Interest rates
- Morpho blog: Introducing the AdaptiveCurveIRM
- Aave governance forum: Risk Stewards stablecoin IRM changes on Aave V3 (September 2, 2026)
- DefiLlama Yields: lending and borrowing rates
- Federal Reserve H.15: Selected interest rates
Educational content, not financial advice. DeFi carries risk, including total loss of funds.