BlockFi vs Compound: What Happened to BlockFi, and How CeFi and DeFi Lending Compare
On this page
BlockFi vs Compound: the status in 2026
This comparison has changed completely since it was first written. BlockFi no longer operates. The centralized lender paused withdrawals in November 2022 after the collapse of FTX, filed for Chapter 11 bankruptcy on November 28, 2022, and has been winding down under a court-approved plan ever since. Compound is still running as a decentralized lending protocol, now mainly through Compound III.
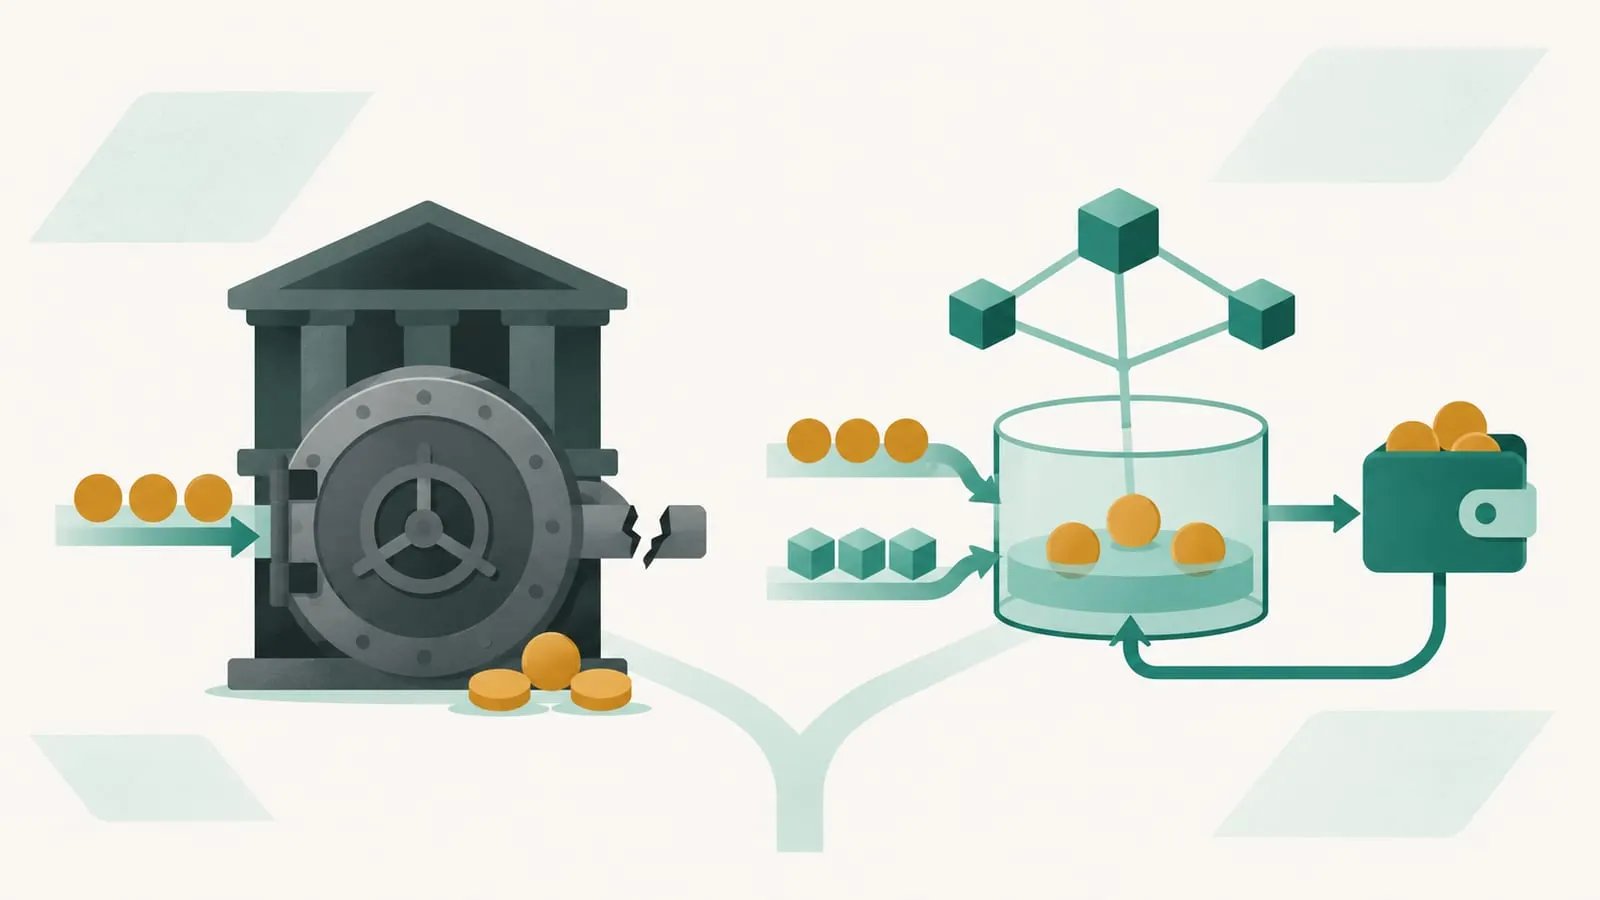
So you can’t choose between them today. What remains useful is the contrast: BlockFi and Compound are textbook examples of the two ways crypto lending works, centralized (CeFi) and decentralized (DeFi). Understanding why one failed and how the other works will help you judge any lending product you come across now.
What BlockFi was
BlockFi, founded in 2017, was a US company that offered three main products:
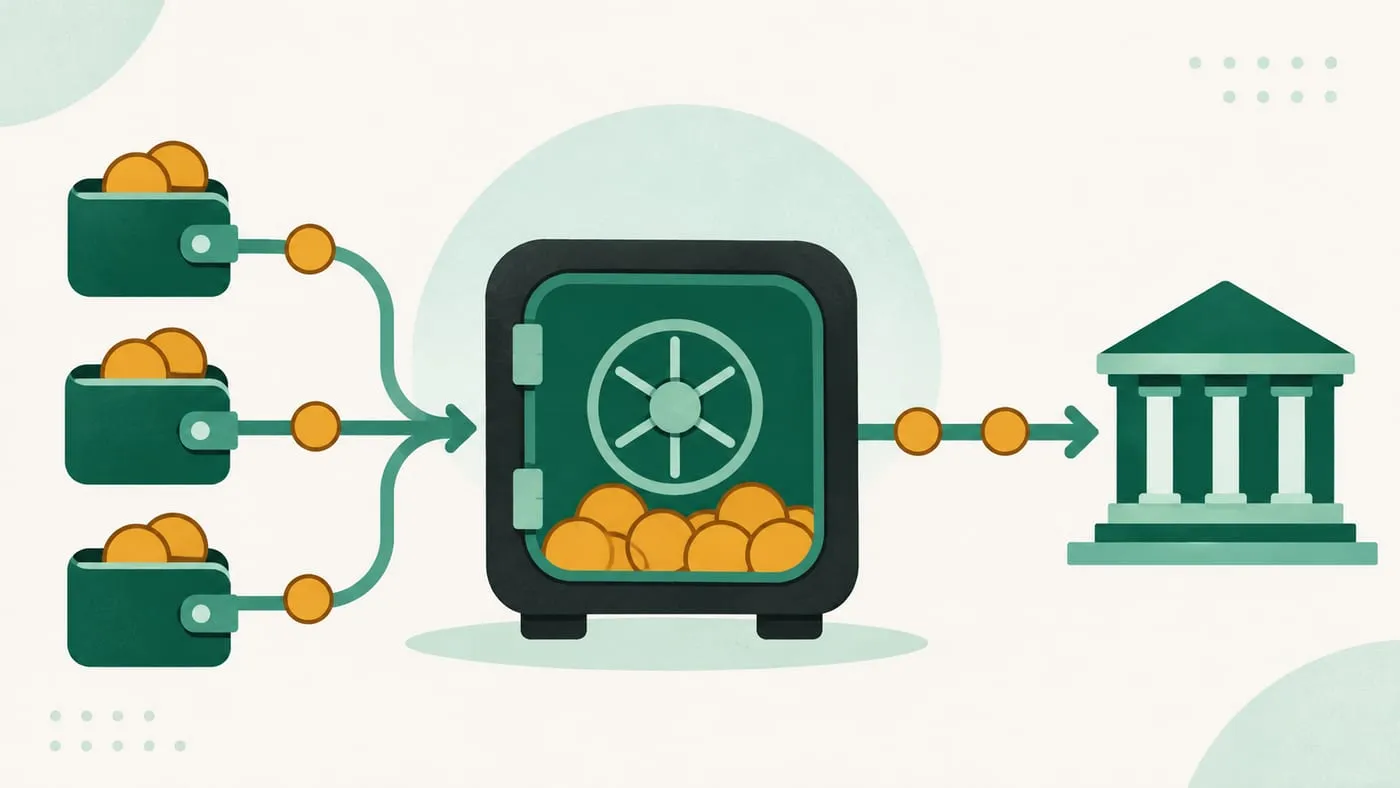
- BlockFi Interest Accounts (BIAs): you deposited crypto or stablecoins and the company paid you interest, which it funded by lending your coins to institutional borrowers and trading firms.
- Crypto-backed loans: you pledged bitcoin or ether as collateral and borrowed US dollars.
- A custodial wallet and trading, plus a rewards credit card.
The key point is that BlockFi held your coins. Your “deposit” was a loan to BlockFi, and your return depended on BlockFi’s lending decisions and its own solvency, much like other centralized lenders such as Celsius.
How BlockFi failed: a timeline
| Date | Event |
|---|---|
| February 2022 | BlockFi agrees to pay $100 million ($50 million to the SEC and $50 million to 32 states) over unregistered sales of its interest accounts, and stops opening new US interest accounts |
| Mid-2022 | Crypto prices fall; hedge fund Three Arrows Capital, a BlockFi borrower, collapses. In July 2022 BlockFi agrees a credit facility of up to $400 million with FTX US (5% interest, junior to customer liabilities) that also gives FTX US an option to acquire it |
| November 2022 | FTX collapses. BlockFi, heavily exposed to FTX and its affiliate Alameda Research, pauses withdrawals, then files for Chapter 11 on November 28 |
| September to October 2023 | The bankruptcy court approves BlockFi’s wind-down plan at a September 26 hearing and enters the written confirmation order on October 3; the plan takes effect on October 24, 2023 and distributions begin, with custodial Wallet customers able to withdraw before interest-account holders |
| July 2024 | The plan administrator sells BlockFi’s FTX claims at a premium to face value and says this allows a final distribution of 100% of allowed customer and general unsecured claims, paid in kind through Coinbase |
Two caveats matter. “100%” refers to allowed claims as valued in the bankruptcy: under the confirmed plan, crypto balances were converted to US dollars at prices on the November 28, 2022 filing date, so customers were not compensated for later price rises. And customers waited well over a year with their money frozen. Full recovery came largely from BlockFi’s claims against FTX, which it sold for more than face value; customers of other failed lenders, such as Celsius and Voyager, recovered only part of what they had deposited.
How Compound works
Compound is a set of smart contracts on Ethereum and several layer-2 networks. Compound III (“Comet”), the current version, runs one market per borrowable base asset, such as USDC or WETH:
- Lenders supply the base asset and earn interest that accrues every second.
- Borrowers post approved collateral, such as ETH or wrapped bitcoin, and borrow the base asset up to that collateral’s borrow collateral factor. Collateral in Compound III does not earn interest.
- Rates come from a formula based on utilization (the share of supplied funds that is borrowed), not from a company’s decision.
- Liquidations happen automatically: if a borrower’s collateral falls below the liquidation threshold, the protocol absorbs the position and sells the collateral at a discount.
There is no account, no KYC at the protocol level, and no company holding your funds. You keep control from your own wallet and can see every market’s deposits, loans and collateral on-chain. As of mid-November 2026, DefiLlama showed roughly $1 billion deposited in Compound III, with the main Ethereum USDC market paying about 3.6% base APY to suppliers. Check DefiLlama for live figures.
BlockFi vs Compound compared
| BlockFi (until 2022) | Compound III (2026) | |
|---|---|---|
| Model | Centralized company (CeFi) | Non-custodial smart contracts (DeFi) |
| Status | Bankrupt, winding down | Operating |
| Who holds your assets | BlockFi | You, via your wallet and the protocol’s contracts |
| How interest was set | By the company, changed periodically | By a utilization-based formula, updated with every transaction |
| Where yield came from | BlockFi re-lending deposits to institutions, often opaquely | Over-collateralized borrowers in a public pool |
| Transparency | Periodic disclosures; loan book not public | Every loan and collateral position visible on-chain |
| Identity checks | KYC required | None at protocol level; front ends may restrict regions |
| Lock-ups | Withdrawals limited and later frozen | Withdraw any time the market has unborrowed liquidity |
| Main risks | Company insolvency, mismanagement, counterparty exposure | Smart-contract bugs, collateral and oracle failures, liquidations |
| Recourse if it fails | Bankruptcy court, years-long process | Usually none beyond protocol reserves or governance decisions |
What the BlockFi collapse teaches
- “Interest account” can mean “unsecured loan to a company.” If a platform can lend out your coins, your risk is its balance sheet and its borrowers. Read the terms for words like “transfer of title” or “rehypothecation”.
- Concentrated counterparties sink lenders. BlockFi’s exposure to a small number of large borrowers (Three Arrows, then FTX and Alameda) proved fatal.
- Bankruptcy is slow even when it ends well. BlockFi creditors were made whole on allowed claims, measured in US dollars at November 2022 prices, but only after a long freeze.
- DeFi swaps company risk for code and market risk. Compound can’t run off with deposits, but bugs, bad collateral and oracle errors can still cost lenders money, and DeFi has no bankruptcy court to sort it out.
For more on the CeFi side, see our review of whether Nexo is a good platform for passive income and the question what are the risks of depositing in DeFi vs BlockFi.
Alternatives if you were a BlockFi user
If you used BlockFi to earn interest or borrow against crypto, the options now fall into two groups:
- DeFi lending protocols such as Aave, Compound III and Morpho. Start with our step-by-step guide to lending crypto on DeFi and our comparison of Aave vs Compound.
- Centralized platforms that still offer crypto yield or loans. Check their licensing, where your assets are held, whether they publish proof of reserves and liabilities, and what happens to your coins if the company fails.
Before borrowing anywhere, understand how collateral works in DeFi lending and what triggers forced liquidation.
Risks
Neither CeFi nor DeFi lending is a savings account with deposit protection. Centralized lenders can freeze withdrawals, fail or misuse funds. DeFi protocols can be exploited, accumulate bad debt from collateral failures, or temporarily block withdrawals when utilization reaches 100%. Rates on both change over time and are not promised. See DeFi lending risks for a full list. This page explains how these products work and is not financial advice.
Frequently asked questions
Is BlockFi still operating?
No. BlockFi stopped normal operations in November 2022, went through Chapter 11 bankruptcy, and its platform is no longer active. Its remaining work is administering distributions to creditors under the confirmed plan; BlockFi's last customer notice asked holders to complete identity verification by May 27, 2025 to receive remaining distributions. We could not confirm from the court docket whether the case has formally closed.
Did BlockFi customers get their money back?
In July 2024 the plan administrator said the sale of BlockFi's FTX claims would allow a final distribution of 100% of allowed customer and general unsecured claims. That means allowed claims valued in US dollars at crypto prices on the November 28, 2022 filing date, not at today's prices, and customers waited well over a year; international customers could face extra identity checks.
Why did BlockFi go bankrupt?
BlockFi was hit by the 2022 crypto lending crisis, including losses tied to Three Arrows Capital, and then took a credit line from FTX. When FTX collapsed in November 2022, BlockFi had significant exposure to FTX and its affiliate Alameda Research and could not meet withdrawals.
Is Compound safer than BlockFi was?
It has different risks rather than no risk. Compound doesn't depend on one company's solvency or honesty, and its positions are visible on-chain, but users face smart-contract bugs, bad collateral, oracle errors, liquidations and temporary withdrawal limits at high utilization.
What happened to BlockFi Interest Accounts?
In February 2022 BlockFi agreed to pay $100 million to the SEC and 32 states, which treated the accounts as unregistered securities, and stopped opening new US interest accounts. In bankruptcy, interest-account balances were treated differently from custodial Wallet balances, and Wallet customers were able to withdraw earlier.
Sources
- BlockFi: BlockFi estate will return 100% of eligible claims (July 2024)
- BlockFi: Verify identity by May 27, 2025 to secure remaining BlockFi distributions
- U.S. Bankruptcy Court, D.N.J., In re BlockFi Inc.: First-day declaration of Mark A. Renzi (Doc. 17, November 28, 2022)
- U.S. Bankruptcy Court, D.N.J., In re BlockFi Inc.: Notice of occurrence of the Effective Date (Doc. 1788, October 24, 2023)
- U.S. Bankruptcy Court, D.N.J., In re BlockFi Inc., No. 22-19361: Order confirming the Third Amended Joint Chapter 11 Plan (Doc. 1660, October 3, 2023)
- PR Newswire: BlockFi Plan Administrator Announces Claims Sale and Full Customer Recovery (July 22, 2024)
- The Block: BlockFi can begin repaying creditors after emerging from bankruptcy (October 2023)
- Simpson Thacher: BlockFi announces $100 million settlement with SEC and state regulators (February 2022)
- Compound III documentation: Interest rates
- Compound III documentation: Collateral and borrowing
- DefiLlama: Compound V3 protocol data
Educational content, not financial advice. DeFi carries risk, including total loss of funds.