Fixed APR vs Variable APR: What They Mean and How to Choose
On this page
The short answer
A fixed APR stays the same for the agreed term of the loan. A variable APR is tied to a benchmark interest rate and moves when that benchmark moves, so your interest cost can go up or down. Fixed rates give you predictability; variable rates often start lower but pass the risk of rising rates to you.
APR, or annual percentage rate, is the yearly cost of borrowing. The US Consumer Financial Protection Bureau (CFPB) describes it as a measure of the interest rate plus additional fees charged with the loan, which is why it is the better number for comparing loans. This guide explains both types, how variable rates are calculated, when each tends to fit, and how the same idea works in crypto lending. It is general information, not financial advice.
What is a fixed APR?
With a fixed APR, the rate is set when you take out the loan and doesn’t change for the agreed term. For a fixed-rate mortgage, the CFPB puts it simply: the interest rate is set when you take out the loan and will not change. Your scheduled payments on an installment loan stay the same, which makes budgeting easier.
Common examples: fixed-rate mortgages, most auto loans and many personal loans.
What to watch for: “fixed” applies to the stated term. Introductory or promotional rates end, missed payments can trigger penalty rates on some products, and revolving credit such as credit cards has its own rules. Read the agreement for when, if ever, the rate can change.
What is a variable APR?
A variable APR (also called an adjustable rate) has two parts:
Variable APR = index + margin
- The index is a benchmark rate the lender doesn’t control. In the US, many credit cards and home equity lines use the prime rate, which the Federal Reserve’s H.15 release showed at 7.00% as of November 12, 2026.
- The margin is a fixed number of percentage points the lender adds, based largely on your credit profile.
If the index rises by half a point, your APR rises by half a point at the next adjustment. Adjustable-rate mortgages adjust on set dates and may have caps limiting how much the rate can change at each adjustment or over the life of the loan; the CFPB notes that some ARMs also limit how far the rate can drop.
Credit cards follow their own rules in the US. Most card APRs are variable and rise automatically when the prime rate rises. For other increases, the CFPB says issuers generally can’t raise the rate on new transactions during the account’s first year, must give 45 days’ notice before raising it on new purchases after that, and generally can’t raise the rate on an existing balance unless a promotional rate ends, the index rises, or a payment is more than 60 days late.
Common examples: most credit cards, home equity lines of credit, adjustable-rate mortgages and some private student loans.
Fixed vs variable APR at a glance
| Fixed APR | Variable APR | |
|---|---|---|
| Rate changes? | No, for the agreed term | Yes, with an index |
| Starting rate | Usually higher | Usually lower |
| Payment predictability | High | Low to medium |
| Who carries rate risk | The lender | You, the borrower |
| Benefits if rates fall | No (unless you refinance) | Yes, automatically |
| Typical products | Fixed mortgages, auto loans, personal loans | Credit cards, HELOCs, ARMs |
| Crypto equivalent | Fixed-rate DeFi products, some CeFi loans | Aave, Compound, Morpho borrowing |
A worked example
Say you borrow $10,000 for two years and, to keep the math simple, compare one year’s interest at a time on the full balance:
- Fixed at 8%: about $800 in year one and $800 in year two, $1,600 in total.
- Variable starting at 7%: about $700 in year one. If the index rises two points, year two costs about $900, also $1,600 in total. If it rises three points, you pay more than the fixed loan; if it stays flat or falls, you pay less.
The variable loan is cheaper only if rates don’t rise much, and nobody can reliably forecast that. Real loans amortize and compound, so actual figures differ; use the lender’s disclosed APR and payment schedule.
Pros and cons
Fixed APR
Pros
- Predictable payments for the whole term.
- Protected if market rates rise.
Cons
- Usually a higher starting rate.
- You don’t benefit if rates fall, unless you refinance (which can cost fees).
Variable APR
Pros
- Usually a lower starting rate.
- Your cost falls automatically if the index falls.
Cons
- Payments can rise, sometimes sharply, at a bad time for your budget.
- Harder to plan long-term costs.
How to choose
A fixed APR tends to fit when:
- you need stable payments to budget,
- you plan to borrow for many years, or
- a rate increase would cause real hardship.
A variable APR tends to fit when:
- you expect to repay quickly, so there’s little time for rates to rise,
- the starting discount is meaningful and you could absorb increases, or
- the variable loan has caps you’re comfortable with.
Whatever you choose, compare APR to APR across lenders, check fees and prepayment terms, and model what happens if a variable rate rises by two or three points.
APR vs interest rate vs APY
- Interest rate: the cost of borrowing the principal, without fees.
- APR: the interest rate plus certain fees, expressed per year. The CFPB advises comparing APRs only with other APRs.
- APY: the yearly rate including compounding. It is usually quoted for savings and yields, and is higher than the APR when interest compounds more than once a year.
Crypto platforms mix these labels, so check which one you’re looking at. See what APY means in crypto and how to convert an interest rate to APY.
Fixed vs variable rates in crypto lending
In DeFi lending, variable is the default, and it is far more variable than a credit card:
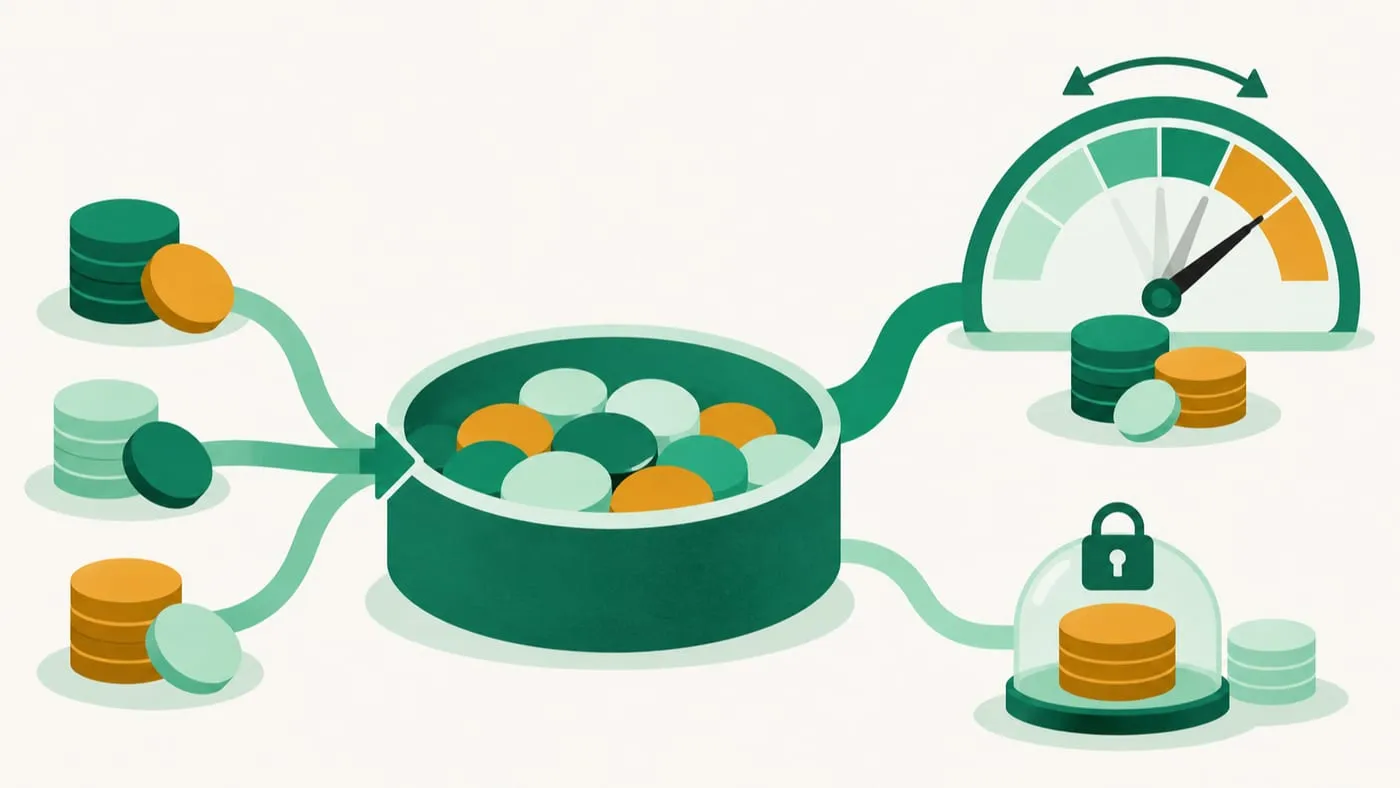
- Rates can change with every transaction, not once a month. Protocols such as Aave and Compound III set borrow rates from utilization, the share of a pool that is borrowed, and rates jump steeply once utilization passes a set “kink.” A loan at 5% today can cost much more next week. Our guide to what determines interest rates on crypto lending platforms explains the mechanics.
- Aave’s “stable rate” is gone. Aave once offered a stable borrow rate alongside the variable one; Aave V3.2 (October 2024) removed the legacy stable-rate logic, so Aave V3 borrowing is variable. See how lending works on Aave.
- Fixed rates come from separate products. Pendle splits yield-bearing tokens into a principal token (PT) and a yield token (YT). Pendle describes PT as essentially a zero-coupon bond: it trades at a discount and redeems 1:1 for its accounting asset at maturity, so buying and holding it locks in a fixed yield in that asset. That is a fixed rate for lenders, not for borrowers. Morpho Midnight, Morpho’s fixed-rate, fixed-term lending protocol, held roughly $220 million on DefiLlama in mid-November 2026, mostly on Ethereum. On-chain credit platforms such as Wildcat let borrowers set fixed rates for their markets. Some centralized lenders quote fixed rates on crypto-backed loans for a set term.
- Rate hedges exist but are niche. Interest rate swaps in DeFi let users trade fixed for floating exposure, with thin liquidity.
For a beginner’s overview of borrowing on-chain, see DeFi loans explained for beginners and the wider interest rates hub.
Risks to keep in mind
- Variable-rate shock: in traditional loans, a rising index can raise payments for years; in DeFi, a spike in utilization can multiply your borrow rate within hours.
- Liquidation: crypto loans are usually collateralized, so a falling collateral price can trigger liquidation regardless of whether your rate is fixed or variable.
- Fixed isn’t free: fixed-rate crypto products carry their own smart contract and liquidity risks, and selling a fixed-rate position before maturity happens at the market price.
- Fees: origination fees, prepayment penalties and gas costs change the true cost of a loan.
This page explains how rate types work and is not financial or lending advice. For more on borrowing, see the Lending & Borrowing hub.
Frequently asked questions
What does fixed APR mean?
It means the annual percentage rate on your loan is set when you take it out and doesn't change for the agreed term, so your interest cost is predictable. Check the loan terms for exceptions, such as a promotional period ending or penalty rates after missed payments.
What does variable APR mean?
It means your rate is tied to an index, such as the prime rate, plus a margin set by the lender. When the index moves, your APR moves with it, usually after a set adjustment date or billing cycle.
Is a fixed or variable APR better?
Neither is better in general. Fixed suits people who need predictable payments or expect rates to rise and plan to borrow for a long time. Variable can cost less if rates stay flat or fall, or if you'll repay quickly, but you carry the risk of increases.
Can a fixed APR ever change?
The rate on a fixed-rate installment loan, such as a fixed-rate mortgage, doesn't change. Credit cards are different: in the US, the CFPB says an issuer generally can't raise your rate on new transactions in the first year, and after that must give 45 days' notice before raising it on new purchases. Promotional rates also end, and a payment more than 60 days late can trigger a higher rate.
Do credit cards have fixed or variable APRs?
Most US credit cards have variable APRs tied to the prime rate, so your rate can rise when prime rises without the 45-day advance notice required for other increases. Your card agreement and monthly statement say which type you have.
What is the difference between APR and APY?
APR is the yearly rate including certain fees, without compounding. APY includes the effect of compounding, so it is higher than the APR whenever interest compounds more than once a year. Borrowing costs are usually quoted as APR and savings or yields as APY.
Are crypto loan rates fixed or variable?
On DeFi lending protocols such as Aave, Compound and Morpho, borrow rates are variable and update with every transaction based on how much of the pool is borrowed. Fixed-rate options exist through separate protocols, and some centralized crypto lenders quote fixed rates for a set term.
Sources
- CFPB: What is the difference between a fixed-rate and adjustable-rate mortgage (ARM) loan?
- CFPB: What is the difference between a loan's interest rate and its APR? (auto loans)
- CFPB: When can my credit card company increase my interest rate?
- Federal Reserve H.15: Selected interest rates (bank prime loan rate)
- Aave documentation: Changelog (V3.2 removal of stable rate)
- Compound III documentation: Interest rates
- Pendle documentation: PT (Principal Token)
- DefiLlama: Morpho Midnight
Educational content, not financial advice. DeFi carries risk, including total loss of funds.