Stablecoin Yield Farming: What It Is and How It Works
On this page
What is stablecoin yield farming?
Stablecoin yield farming is depositing dollar-pegged tokens, such as USDC, USDT or USDS, into decentralized finance (DeFi) protocols so that they earn a return. You lend them to borrowers, lock them in a savings contract or add them to a trading pool, and you are paid in interest, fees or reward tokens.
Because the deposit is meant to stay worth about $1 per token, you avoid most of the price swings that come with farming volatile coins like ETH. That is the appeal. The catch is that “stable” describes the price target, not the safety of the protocols you use. As of November 2026, the largest Ethereum lending and savings markets paid roughly 3–4.5% base APY, according to DefiLlama.
This page explains the mechanics: where the money comes from, how each method works step by step, and what the numbers mean. If you want to judge whether it is worth doing at all, read our companion piece, is stablecoin yield farming a good investment?.
A quick refresher on stablecoins
A stablecoin is a token designed to hold a steady value, usually $1. The main designs are:
- Fiat-backed (USDC, USDT): an issuer holds cash and short-term government debt and redeems tokens for dollars.
- Crypto-backed (DAI, USDS): users lock more crypto than they borrow, and liquidations keep the system solvent.
- Synthetic or strategy-backed (for example Ethena’s USDe): the dollar value comes from hedged derivatives positions rather than cash in a bank.
- Algorithmic: supply rules try to hold the peg without full collateral. This design failed spectacularly with TerraUSD in May 2022.
Which stablecoin you farm with matters as much as where you farm it, because a depeg hits your principal directly. Our guide to how stablecoins earn interest covers the backing side in more detail.
How stablecoin yield farming works: the three core mechanisms
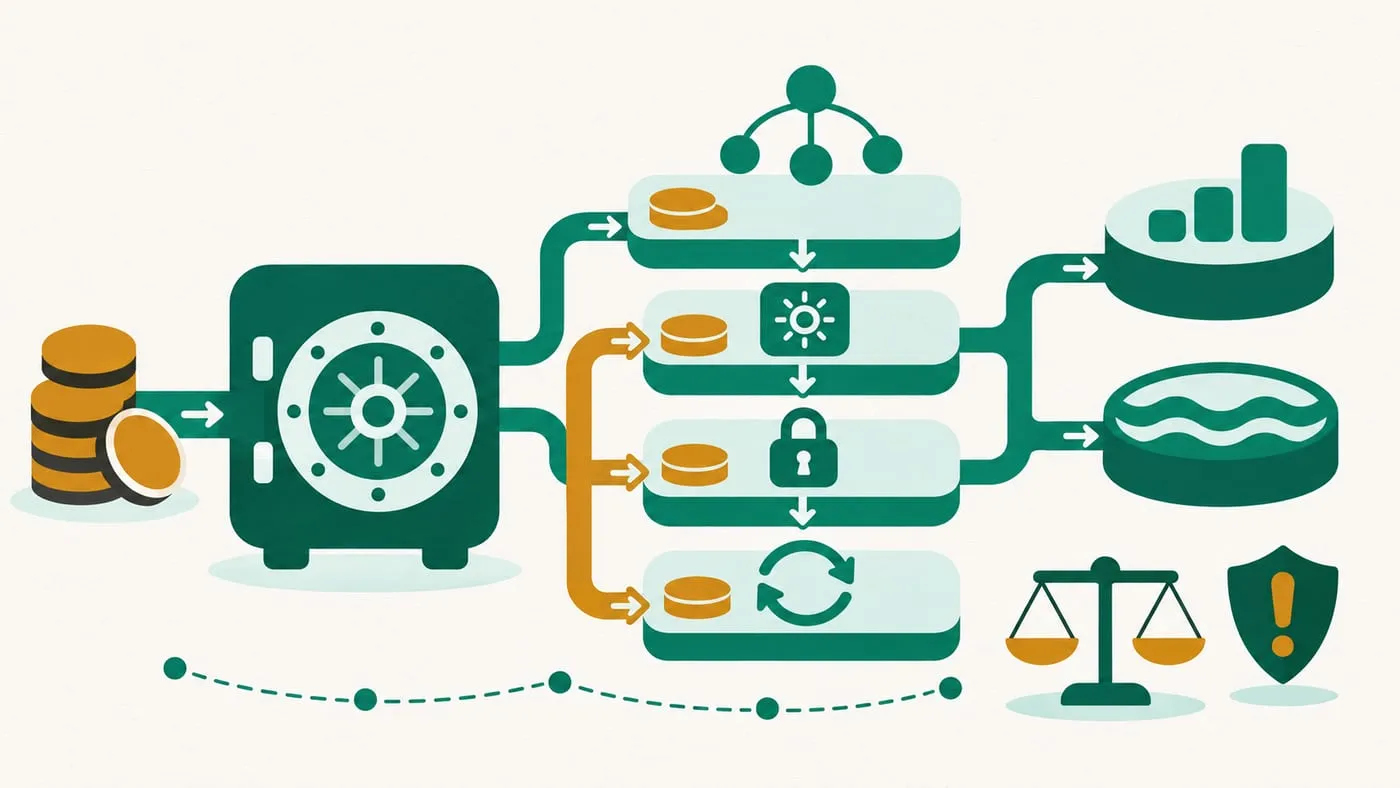
Almost every stablecoin farm is built on one of three engines, sometimes stacked together.
1. Lending: borrowers pay you interest
On a lending market such as Aave or Compound, you supply stablecoins to a shared pool. Borrowers post collateral, usually ETH or other crypto worth more than their loan, and borrow from the pool. Their interest flows to suppliers, minus a cut kept by the protocol (the reserve factor).
How the rate is set:
- The protocol measures utilization: the share of the pool currently borrowed.
- A rate curve turns utilization into a borrow rate. Rates rise gently until an “optimal” utilization point, then steeply above it, to pull in deposits and push out borrowers.
- Suppliers earn roughly borrow rate × utilization × (1 − reserve factor).
On Aave, your deposit is represented by an aToken (for example aUSDC) whose balance grows every block. On Compound III, each market has one borrowable base asset, and only suppliers of that base asset earn interest. More on the rate mechanics in what determines interest rates on crypto lending platforms.
Example: if a USDC pool is 80% utilized at a 5% borrow rate with a 10% reserve factor, suppliers earn about 5% × 0.8 × 0.9 = 3.6%. In mid-November 2026, Aave V3’s main Ethereum USDC market showed about 4.5% supply APY and about 5.2% borrow APY on DefiLlama.
2. Savings tokens: a protocol shares its revenue
A savings token wraps a stablecoin in a vault that grows in value over time. You deposit, receive a share token, and redeem it later for more than you put in.
- sUSDS (Sky, formerly MakerDAO) accrues the Sky Savings Rate, which Sky governance sets and funds from the protocol’s revenue. It showed about 3.8% APY on DefiLlama in November 2026.
- sUSDe (Ethena) earns mainly from derivatives funding and basis spreads, so its rate swings more; it showed about 5% in November 2026, and unstaking directly involves a cooldown.
You do not pick borrowers or manage anything, but the rate can be changed or cut at any time.
3. Liquidity pools: traders pay you fees
A stablecoin liquidity pool holds two or more stablecoins so traders can swap between them. Curve’s stableswap pools are the best-known design: they concentrate liquidity near a 1:1 price, so large swaps move the price very little.
As a liquidity provider (LP), you deposit coins, receive LP tokens representing your share, and earn part of every swap fee. Many pools also pay extra reward tokens, which is where the term “farming” comes from: you stake your LP tokens in a gauge or farm contract to collect them.
Example (illustrative): a pool with $50 million of liquidity, $20 million of daily volume and a 0.01% fee kept by LPs generates about $2,000 a day, or roughly $730,000 a year, which is about 1.5% on the pool before any rewards. The rest of an advertised APY usually comes from incentives.
While every coin in the pool holds its peg, impermanent loss is minimal. If one coin depegs, traders sell it into the pool and LPs end up holding mostly the weaker coin; see how impermanent loss works with a stablecoin.
Stacked strategies: vaults, aggregators and loops
On top of these engines sit more complex products. Yield aggregators and curated vaults move your deposit between lending markets or auto-compound pool rewards. Fixed-rate protocols such as Pendle let you lock in a rate until a maturity date. Leveraged “looping” borrows against a deposit to redeposit it, multiplying both yield and risk; see leveraged yield farming explained. Each layer adds another set of contracts and often a manager whose choices you are trusting.
Typical stablecoin yields in 2026
| Method | Who pays you | Typical base yield (Nov 2026) | Main extra risk |
|---|---|---|---|
| Lending (Aave V3, Compound III on Ethereum) | Borrowers | Roughly 3–4.5% APY, variable | Pool fully borrowed, protocol exploit |
| Savings token (sUSDS) | Protocol revenue, set by governance | About 3.8% APY | Rate cuts, issuer and governance risk |
| Synthetic-dollar savings (sUSDe) | Derivatives funding and basis | About 5% APY, more volatile | Negative funding, exchange and custody risk |
| Stablecoin LP pools | Traders’ swap fees, plus incentives | Fees are often low single digits; total varies widely | Depegs, reward-token price |
| Incentive farms and loops | Token emissions, leverage | Can be much higher, temporarily | Emissions end, liquidation |
Figures are snapshots from DefiLlama Yields and change daily. Dashboards usually separate base yield (from real activity) from reward yield (from token emissions); the base figure is what is left when incentives stop. They also usually quote APY, which assumes compounding, rather than APR; see what APY means in crypto.
How to start stablecoin yield farming: step by step
This is how the process works in practice. It is a description, not a recommendation to deposit.
- Choose a network. Ethereum mainnet has the deepest markets but the highest gas fees. Layer 2s and other chains are cheaper but add bridging steps and often thinner liquidity.
- Set up a self-custody wallet and fund it with stablecoins plus a little of the network’s gas token (ETH on Ethereum and most L2s). Protect your seed phrase offline; no legitimate protocol will ask for it.
- Pick a method and protocol. Check its age, audits, incident history and the stablecoin it uses. Reach the app by typing its address or using a bookmark, not through ads or links in messages.
- Approve the token. Your wallet asks you to let the protocol’s contract spend your stablecoin. Approving only the amount you deposit limits damage if that contract is ever compromised.
- Deposit. You receive a receipt token: an aToken, a savings token, or LP tokens.
- Stake LP tokens if needed. For pool rewards, LP tokens usually have to be staked in a separate gauge or farm contract.
- Monitor. Watch the rate, the stablecoin’s peg, the pool’s utilization and protocol announcements. Claim and handle rewards if they are not auto-compounded.
- Withdraw. Redeem the receipt token. If a lending pool is fully borrowed, you may have to wait for repayments or new deposits.
Costs matter at small sizes. At 4%, $500 earns about $20 a year, which a few Ethereum mainnet transactions can consume. For where to deposit, see which platforms are used for yield farming stablecoins.
DeFi vs centralized stablecoin rewards
Exchanges and fintech apps also pay rewards on stablecoin balances. The difference is custody: with a centralized platform, you rely on the company to stay solvent and honest, as the 2022 failures of Celsius and BlockFi showed. With DeFi you hold your own keys and the rules are in public code, but you carry the technical risks yourself. Regulation is also shifting: the US GENIUS Act, signed in July 2025, bars licensed payment-stablecoin issuers from paying holders interest simply for holding their coins, though it does not directly cover DeFi lending. Our investment page, linked above, follows that debate in more detail.
Risks of stablecoin yield farming
- Smart contract risk: a bug or exploit can drain a protocol. Audits reduce this but do not remove it.
- Depeg risk: in March 2023, USDC briefly traded around $0.87–0.88 after Circle disclosed reserves at the failed Silicon Valley Bank; LP pools absorbed the shock first.
- Liquidity risk: a fully borrowed lending pool, a cooldown or a withdrawal queue can delay your exit.
- Counterparty risk: issuers can freeze tokens, and vault curators or off-chain managers can make losing bets.
- Incentive risk: reward tokens can fall in value, and emissions end.
- Operational risk: phishing sites, malicious approvals and lost seed phrases cause many losses.
Stablecoin farming is not a savings account with deposit protection. For the full list, read our guide to the risks of yield farming. Taxes also apply in most countries; see how yield farming is taxed.
Key terms
- APY / APR: annual yield with and without compounding.
- Utilization: the share of a lending pool that is borrowed; it drives the rate.
- Base vs reward yield: income from real activity versus token emissions.
- LP token: your receipt for a share of a liquidity pool.
- Peg: the target price, usually $1.
For more, browse the yield farming topic hub or start from the yield farming and staking guide.
Frequently asked questions
What is stablecoin yield farming?
It is the practice of depositing stablecoins into DeFi protocols, such as lending markets, savings tokens or liquidity pools, to earn a return. The return comes from borrowers' interest, swap fees, protocol revenue or token incentives.
How much can you earn yield farming stablecoins?
As of November 2026, blue-chip lending markets for USDC and USDT on Ethereum and the Sky Savings Rate on sUSDS paid roughly 3–4.5% base APY on DefiLlama. Some markets add 1–2% in token rewards. Rates are variable and change daily.
Is stablecoin yield farming passive?
Lending and savings tokens need little attention once deposited, but you still need to watch for rate changes, depegs and protocol news. Liquidity pools and incentive farms need more monitoring, and leveraged strategies need constant attention.
Do I need a wallet to yield farm stablecoins?
For DeFi, yes: you need a self-custody wallet such as a browser or mobile wallet, plus a little of the network's native token to pay gas. Centralized exchanges also offer stablecoin rewards without a wallet, but they hold your funds.
What is the safest way to farm stablecoins?
No method is free of risk. Lower-risk approaches generally mean established lending markets or savings tokens, widely used stablecoins, no leverage, and spreading deposits across protocols, while sizing the position as if you could lose it.
Sources
Educational content, not financial advice. DeFi carries risk, including total loss of funds.