Perpetual Contracts in Crypto: How Perps, Funding Rates and Liquidation Work (2026)
On this page
The short answer
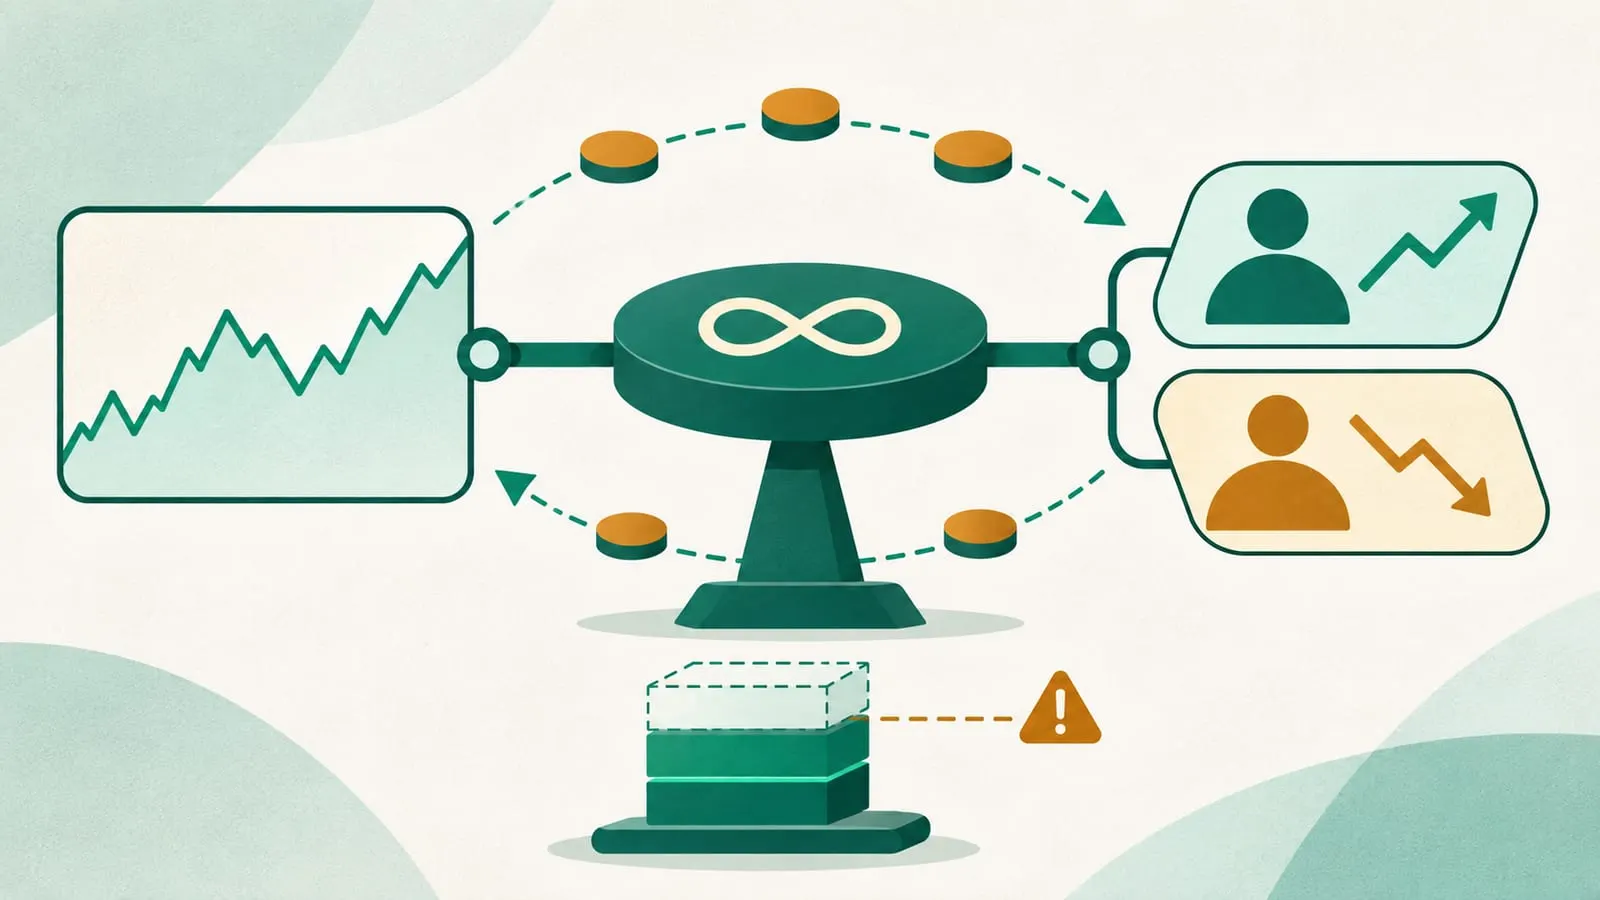
A perpetual contract, or perp, is a futures contract with no expiry date. You post margin, take a long or short position on an asset’s price, and keep it open as long as you like, provided your margin covers your losses. Instead of converging with the spot price at expiry like a dated future, a perp stays close to spot through funding payments exchanged between longs and shorts at regular intervals. You never own the coin, and with leverage a small move against you can wipe out your margin.
Perps are the main way crypto is traded with leverage worldwide. The CFTC describes crypto asset perpetual contracts as derivatives with no fixed expiration date, designed to maintain price parity with the spot price of the asset they reference.
What has changed since this article was first written
The original version of this page needs several corrections:
- Funding is not a “basis swap” of interest rates between two coins. It is a payment between longs and shorts based on how far the perp trades from spot. It is explained below.
- Futures don’t usually force delivery. Most crypto futures, including CME’s, are cash-settled, so no coins change hands at expiry.
- The exchange list is out of date. BlockFi, which it listed, filed for bankruptcy in November 2022 and wound down. BitMEX, which pioneered crypto perps, closed permanently on September 23, 2026. Coinbase reaches perps in the US through regulated products described below.
- The old claims that dApps offer returns without risk, and that algorithmic trading is a passive income source, were wrong and have been removed.
A short history
The idea of a perpetual future is older than crypto. Economist Robert Shiller proposed perpetual futures in a 1993 Journal of Finance paper (circulated as a working paper in 1992), as a way to create markets for assets like real estate whose prices are hard to observe.
The crypto version arrived on May 13, 2016, when BitMEX launched XBTUSD, a bitcoin perpetual swap offering up to 100x leverage, with a funding mechanism replacing expiry. The design spread to nearly every large crypto exchange and later to on-chain venues. On July 23, 2026, the board of HDR Global Trading, BitMEX’s owner and operator, announced that the exchange would shut down permanently. New sign-ups stopped at once, trading was limited to reducing positions from August 26, and the exchange closed on September 23, 2026, but the contract it introduced is now the dominant crypto derivative. In 2025 and 2026 perpetuals also reached US-regulated exchanges.
How perpetual contracts work
Margin, leverage and liquidation
You don’t pay the full value of the position. You post initial margin, and leverage is the position’s value divided by your margin. At 50x you post 2% of the position’s value, and a move of about 2% against you erases it.
Every venue sets a maintenance margin, the minimum equity you must keep. Fall below it and the venue’s liquidation engine closes the position, measured against a mark price built from several spot markets rather than the venue’s last trade. Because of the maintenance margin, liquidation comes before your margin reaches zero: roughly a 9% move at 10x. Our forced liquidation entry has the full table, and the answer on leverage and trading time frame shows how often moves of that size happen.
Funding rates
Since a perp never expires, nothing forces its price to meet spot. Funding does that job:
- Perp above spot (positive funding): longs pay shorts. This makes holding a long more expensive and rewards shorts, pulling the price down toward spot.
- Perp below spot (negative funding): shorts pay longs, pulling the price up.
The exchange typically doesn’t keep funding; it moves between traders. The interval varies: Hyperliquid pays funding every hour at one eighth of an eight-hour rate, while Kalshi calculates funding every eight hours. On Hyperliquid each payment is position size × oracle price × funding rate, and the rate combines a premium (how far the perp trades from the oracle) with a fixed interest component of 0.01% per eight hours, which Hyperliquid describes as 11.6% APR paid to shorts. Funding is capped at 0.5% per hour, a looser cap than centralized exchanges typically use, so in a lopsided market funding can become very expensive quickly.
Example. You hold a $10,000 long with $1,000 of margin (10x). If funding sits at 0.01% per eight hours, you pay $1 every eight hours, about $3 a day or roughly $1,100 a year. That is more than your entire margin, even though the rate sounds tiny, because it is charged on the full position. Funding can also turn in your favor, and it changes constantly.
Traders also watch funding and open interest (the total value of open perp positions) as rough signs of how crowded one side is. Persistently high positive funding means longs are paying heavily to stay in. Some funds and protocols run a “basis” or funding trade, holding spot and shorting the perp to collect funding; that income disappears or reverses when funding turns negative, and it carries exchange and liquidation risk on the short leg.
Linear vs inverse perps
Linear perps are margined and settled in dollars or a stablecoin such as USDC, so profit and loss is in dollars. Inverse (coin-margined) perps use the coin itself as collateral. In an inverse long, your collateral loses value at the same time as your position, compounding losses on a fall.
Perpetuals vs dated futures vs spot margin
| Perpetual contract | Dated future | Spot margin | |
|---|---|---|---|
| Expiry | None | Fixed date, then settles | None, but the loan accrues interest |
| Tracks spot via | Funding payments | Convergence at expiry | You hold the actual asset |
| Running cost | Funding (can be paid or received) | Rolling cost if you extend past expiry | Borrow interest |
| Own the coin? | No | No (usually cash-settled) | Yes, bought with borrowed money |
| Liquidation | Yes | Yes | Yes |
For dated contracts, see how to trade crypto futures and whether to let futures expire. For borrowing-based margin, see the margin trading topic. Perps are also the most common tool for shorting crypto.
Where perpetuals trade
- Offshore centralized exchanges carry most volume. By reported derivatives volume, Binance is the largest, followed by OKX and Bybit (see the most popular margin trading platforms). Most exclude US residents.
- On-chain perp exchanges let you trade from a self-custody wallet. Hyperliquid is the largest by volume; dYdX runs perps on its own chain, as covered in margin trading on dYdX. Their official front ends restrict US persons, and they add smart contract and oracle risk.
- US-regulated exchanges, covered next.
Perpetual contracts in the US (as of November 2026)
US crypto derivatives are overseen by the CFTC, and US persons should use CFTC-registered exchanges reached through registered brokers.
- Bitnomial self-certified the first US-listed bitcoin perpetual in April 2025, initially for institutional participants.
- Coinbase Derivatives launched perpetual-style futures in July 2025: five-year contracts with funding-style adjustments and 24/7 trading. In June 2026, at the request of Coinbase Derivatives and Bitnomial, CFTC staff gave no-action relief letting exchanges remove expiry dates from such contracts under conditions; check the exchange’s current contract specifications for whether that has happened.
- Kalshi: on May 29, 2026 the CFTC approved Kalshi’s cash-settled bitcoin perpetual (BTCPERP) by Commission order, rather than letting it take effect through self-certification as Bitnomial’s did. The order notes that the perpetual design may not suit all asset classes. A CFTC policy statement issued the same day, which the CFTC says is not binding, states that perpetuals on asset classes not contemplated in the order (it gives agricultural products, precious metals, equities and narrow-based security indexes as examples) should go through CFTC review and approval under Regulation 40.3 rather than self-certification under Regulation 40.2. Kalshi’s help center describes up to 6x leverage, far below offshore limits.
- Legal challenge: in June 2026 CME Group sued the CFTC in federal court, arguing the approval skipped required procedures and that perpetuals should be regulated as swaps. The CFTC moved to dismiss in September 2026, arguing CME lacks standing; as of November 2026 the court had not ruled on that motion, so availability could change.
Our crypto futures guide covers the US picture in more detail, including Deribit access through Coinbase and tax treatment. Using a VPN to reach an offshore venue breaches its terms and leaves you without US regulatory protection.
Risks of perpetual contracts
- Most retail traders of comparable products lose money. National regulators’ data cited by ESMA in 2018 found 74–89% of retail CFD accounts typically lose money; ESMA capped retail crypto CFD leverage at 2:1.
- Fast liquidation. At high leverage, an ordinary hourly move can close your position and take your whole margin. In cascades, liquidations push prices further and trigger more of them.
- Funding and fees. Fees are charged on the full position and funding accrues every interval, which can turn a correct call into a loss if you hold long enough.
- Gaps and wicks. Crypto trades 24/7; stop-losses can fill far from their trigger price.
- Auto-deleveraging. In extreme moves, some venues forcibly reduce profitable traders’ positions to cover losses.
- Counterparty and protocol risk. Exchanges can fail or freeze withdrawals, and on-chain venues can be exploited or have oracles manipulated.
- Regulatory change. US perpetuals are new and under legal challenge, and offshore venues can leave a country with little notice.
- Scams. Apps and “signal” groups promising fixed daily returns from futures trading are a common fraud pattern.
This page explains how perpetual contracts work and is not a recommendation to trade them. If you do, understand the derivatives involved first, treat any margin as money you can afford to lose entirely, and see more guides in Trading, Derivatives & Options.
Frequently asked questions
What is a perpetual contract in crypto?
It is a derivative that tracks a cryptocurrency's price with no expiry date. You post margin, go long or short with leverage, and pay or receive periodic funding that keeps the contract's price close to the spot market.
What is the difference between perpetual and futures contracts?
Dated futures expire and settle on a set date, converging to spot at expiry. Perpetuals never expire and use funding payments instead, so you can hold them indefinitely as long as your margin covers losses and funding.
Who pays the funding rate?
When the funding rate is positive, longs pay shorts; when it is negative, shorts pay longs. The payment is calculated on the full position value, so its cost relative to your margin rises with leverage.
Are perpetual contracts legal in the US?
Yes, on CFTC-regulated exchanges such as Bitnomial and Kalshi, with lower leverage than offshore venues. Most offshore exchanges and the main on-chain perp venues exclude US persons in their terms.
Can you lose more than you put in on perps?
On most crypto venues, losses beyond your margin are absorbed by an insurance fund or auto-deleveraging, so you lose your margin rather than owing more. You can still lose all of it quickly at high leverage.
Sources
- CFTC: CFTC Approves BTCPERP Contract Submitted by KalshiEX (Release 9240-26, May 29, 2026)
- CFTC: Crypto Asset Perpetual Contracts
- Federal Register: CFTC Policy Statement Concerning the Listing of Perpetual Contracts (91 FR 33160, June 3, 2026)
- CFTC: No-action relief for converting perpetual-style futures into true perpetuals (Release 9252-26, Staff Letter 26-19)
- The Block: CFTC files to dismiss CME's lawsuit over crypto perpetual futures (September 2026)
- Markets Media: Bitnomial Exchange self-certifies first US perpetual futures (April 2025)
- Hedgeweek: CME challenges US regulator over approval of crypto perpetual futures
- Hyperliquid Docs: Funding
- The Block: Coinbase Derivatives' US perpetual-style futures begin trading July 21 (2025)
- Kalshi Help Center: What are perpetual futures?
- BitMEX Blog: Announcing the launch of the perpetual XBTUSD leveraged swap (May 2016)
- The Block: BitMEX to shut down permanently (July 23, 2026)
- Shiller (1993), Measuring Asset Values for Cash Settlement in Derivative Markets: Hedonic Repeated Measures Indices and Perpetual Futures, Journal of Finance
- ESMA: Restrictions on CFDs to protect retail investors (2018)
Educational content, not financial advice. DeFi carries risk, including total loss of funds.