DeFi Options Vaults (DOVs): What They Are, How They Work and Their Risks
On this page
What is a DeFi options vault?
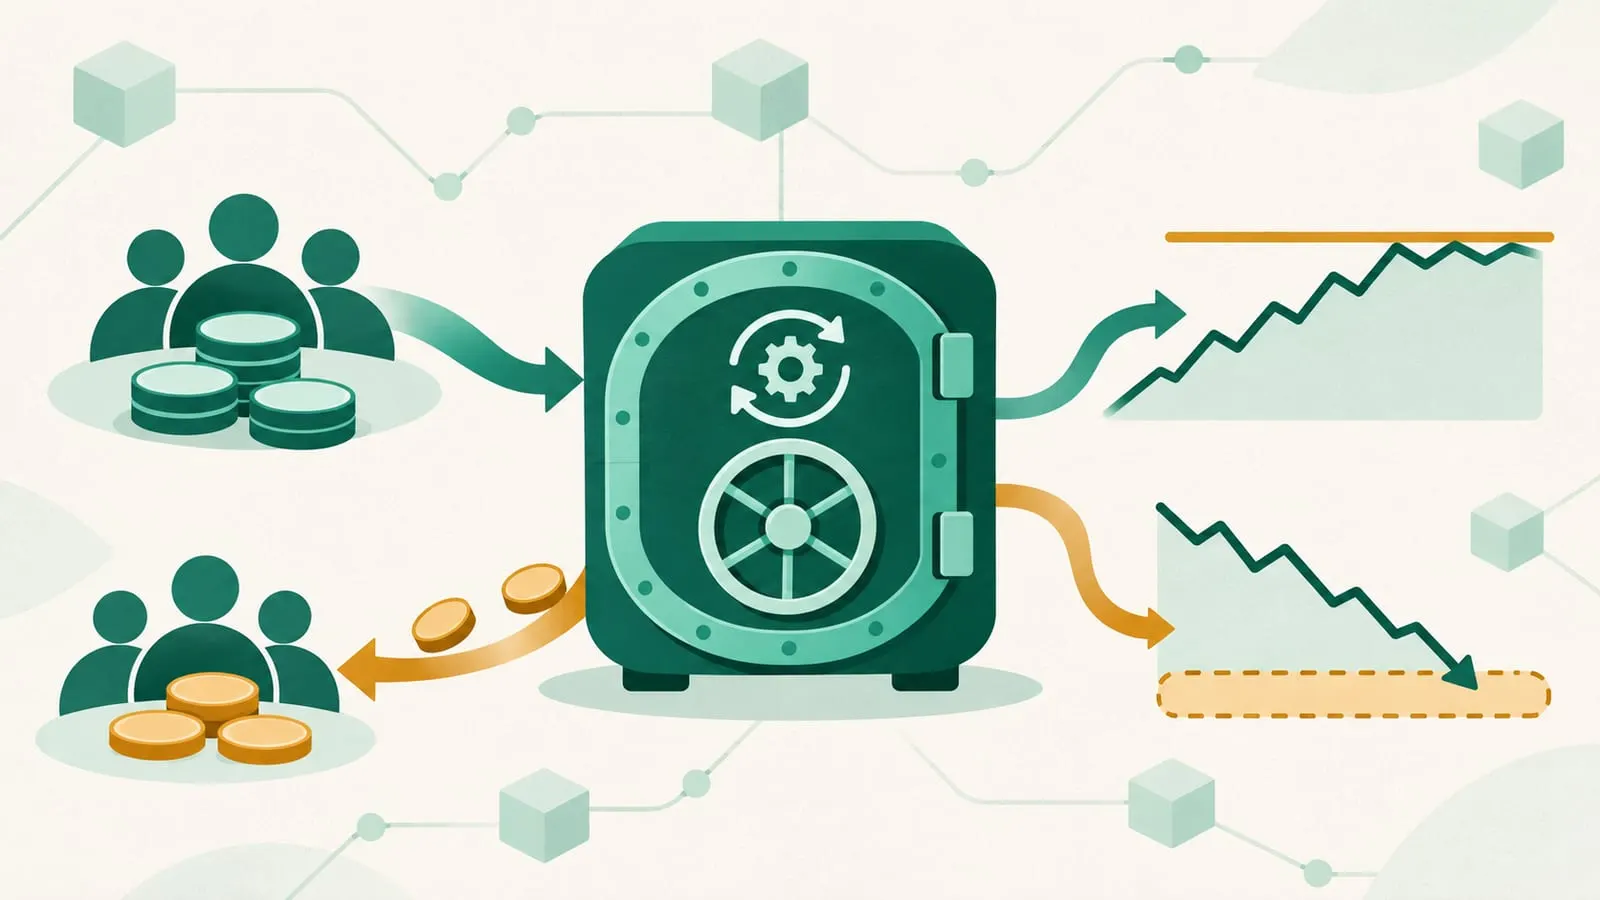
A DeFi options vault (DOV) is a smart contract that pools users’ deposits and automatically runs an options-selling strategy with them. Most DOVs sell covered calls against deposited crypto or cash-secured puts against deposited stablecoins on a fixed schedule, often weekly. Option buyers pay a premium for each option, and that premium is passed back to depositors as yield.
The appeal is automation: instead of choosing strikes, expiries and counterparties yourself, you deposit once and the vault rolls the strategy. The catch is that the premium is payment for real risk. In a strong rally a call vault gives away your upside, and in a crash a put vault ends up holding the falling asset. DOVs are part of the wider DeFi options market.
Options in one minute
An option is a contract giving the buyer the right, but not the obligation, to buy (a call) or sell (a put) an asset at a set strike price on or before an expiry date. The buyer pays the seller a premium up front. Options are derivatives: their value comes from an underlying asset. For more background, see options trading and options trading strategies.
DOV depositors are always on the selling side. Selling options earns steady premiums most of the time and suffers occasional large losses when the market moves past the strike.
How a DOV works
- Deposit. You put an asset into the vault, for example ETH into a covered call vault or USDC into a put-selling vault, and receive a vault share token.
- Strike selection. At the start of each round, the vault picks an expiry and an out-of-the-money strike, typically using a rule based on the asset’s volatility.
- Sale. The vault sells options to buyers, historically through a scheduled auction where market makers bid, and collects the premium.
- Settlement. At expiry, if the option finishes out of the money, the vault keeps the full collateral plus premium. If it finishes in the money, part of the collateral pays the buyer.
- Roll. Premiums are added to the vault and the next round starts. Most vaults only let you withdraw between rounds.
Covered call vault vs put-selling vault
| Covered call vault | Put-selling (cash-secured put) vault | |
|---|---|---|
| You deposit | The asset (e.g. ETH, BTC) | Stablecoins (e.g. USDC) |
| Vault sells | Out-of-the-money calls | Out-of-the-money puts |
| Best case | Price stays below strike: keep asset plus premium | Price stays above strike: keep stablecoins plus premium |
| Bad case | Price rallies past strike: upside above strike is given away. Price crashes: you still hold the falling asset, cushioned only by the premium | Price falls below strike: vault buys the asset at the strike, taking the loss |
| Market view | Neutral to mildly bullish; willing to cap gains | Neutral to bullish; willing to buy at the strike |
Some protocols also ran more complex vaults, such as spreads, principal-protected notes or delta-neutral “basis” vaults, but covered calls and puts were the core.
Where the yield comes from
DOV yield is the option premium. Buyers, mostly professional market makers and traders, pay it for upside or downside exposure or to hedge. Premiums are driven by implied volatility: when markets expect big moves, premiums and vault APYs rise; in calm periods they fall. That is why headline DOV APYs from 2021–22 are a poor guide to today.
Unlike token emissions, premiums are paid by real counterparties, so DOVs were often marketed as “real yield”. But the premium is not free income; it is the fair price of the risk the vault takes. Over a full market cycle, systematic option sellers can underperform simply holding the asset if a few large moves wipe out many weeks of premiums.
Risks of DeFi options vaults
- Strategy risk. Call vaults cap upside, so they lag the market in rallies, while still carrying almost all of the asset’s downside in a crash; put vaults absorb losses in crashes, and losses can exceed premiums collected.
- Smart contract and oracle risk. Vaults depend on contracts that hold collateral and on price oracles that settle options. In December 2025, an attacker exploited an oracle upgrade to set arbitrary expiry prices and drained about $2.7 million from Aevo’s legacy Ribbon vaults. Aevo stopped the vaults and proposed covering part of the shortfall so that affected depositors would take a 19% haircut rather than the roughly 32% the vaults lost.
- Predictable auctions. Vaults that sell at the same time every week, at publicly known sizes, let market makers bid lower, reducing what depositors earn.
- Liquidity and lock-ups. Funds are usually committed until the round ends, so you cannot exit mid-week if the market turns.
- Counterparty and platform risk. Some designs rely on a small set of market makers or an underlying options protocol; if either stops, the vault stops.
- Protocol shutdown. Many DOV protocols from the 2021–22 cycle have closed, and unmaintained vaults are a target for attackers.
- Wrapped-asset risk. Vaults on bridged or liquid staking tokens add depeg and bridge risk.
For the broader picture, see our guide to the risks of yield farming and the smart contract vulnerabilities hub.
DOVs in 2026: what changed
DOVs were one of the hottest DeFi categories in 2021–22. DefiLlama shows Ribbon Finance’s TVL peaking at about $310 million in April 2022. Since then the sector has shrunk and changed shape:
| Protocol | Original model | Status as of November 2026 |
|---|---|---|
| Ribbon Finance (Ethereum) | Weekly covered call and put vaults | Evolved into Aevo; legacy vaults exploited in Dec 2025 and being decommissioned |
| Friktion (Solana) | Structured “Volts” | Sunset in January 2023 |
| Polynomial Earn (Optimism) | Automated options vaults | Earn vaults hold no funds; on February 13, 2026 Polynomial announced it was shutting down Polynomial Chain and Polynomial Trade |
| Dopex SSOVs | Single-staking options vaults | Rebranded as Stryke in 2024, which discontinued the SSOVs in favour of other options products |
| Lyra | Options AMM | Rebranded as Derive in 2024, an order-book options and perps exchange; moved to Derive V3, settling on Ethereum, in October 2026 |
| Rysk (HyperEVM, Ethereum) | RFQ-based covered calls and cash-secured puts | Operating; the largest protocol in DefiLlama’s Options Vault category |
| Thetanuts Finance | Options vaults, now V4 RFQ infrastructure | Operating, with small TVL on DefiLlama |
The main shift is from pooled, auction-based vaults to request-for-quote (RFQ) designs. On Rysk, for example, you choose a covered call or cash-secured put, market makers bid on it through an on-chain RFQ auction, and the premium is sent to your wallet upfront when you accept; your collateral stays locked until expiry. That gives individual control over strike and expiry and removes the predictable weekly auction, but the underlying risk of selling options is unchanged.
Protocols in the table are examples for context, not recommendations. Check each one’s current status, audits and incident history before depositing.
DOVs vs other ways to earn yield
| DOVs | Lending | Liquidity pools | |
|---|---|---|---|
| Yield source | Option premiums | Borrower interest | Trading fees |
| Main market risk | Capped upside or assigned downside | Low (single asset) | Impermanent loss |
| Return pattern | Steady premiums, occasional large losses | Steady, rate floats | Fees minus IL |
| Complexity | Moderate to high | Low | Moderate |
If you are comparing strategies, our yield farming strategies guide covers the alternatives, and Trading, Derivatives & Options collects our options content.
Frequently asked questions
What is a DeFi options vault?
A smart contract that takes deposits and runs an options-selling strategy on a schedule, typically selling out-of-the-money calls against deposited crypto or puts against deposited stablecoins. Option buyers pay premiums, which are passed to depositors as yield.
Are DeFi options vaults safe?
No. Besides smart contract and oracle risk, the strategy itself can lose money: a call vault gives away gains above the strike in a rally, and a put vault ends up buying the asset at the strike in a crash. Several DOV protocols have been exploited or shut down.
Where does DOV yield come from?
From option premiums paid by buyers, mostly professional market makers, who want upside or downside exposure. Premiums are higher when implied volatility is high and fall in calm markets.
What happened to Ribbon Finance?
Ribbon Finance, the best-known DOV protocol, evolved into the Aevo derivatives exchange. In December 2025, its legacy Ethereum vaults were drained of about $2.7 million through an oracle flaw, and Aevo said all Ribbon vaults would be decommissioned.
What is the difference between a covered call vault and a put-selling vault?
A covered call vault holds an asset such as ETH and sells call options on it, earning premiums but capping upside. A put-selling vault holds stablecoins and sells put options, earning premiums but buying the asset at the strike price if it falls below it.
Sources
- The Block: Aevo's legacy Ribbon DOV vaults exploited for $2.7 million following oracle upgrade
- Rysk documentation
- Thetanuts Finance documentation (V4)
- DefiLlama: Rysk V12 (Options Vault category)
- DefiLlama: Ribbon
- DefiLlama: Friktion (sunset January 2023)
- DefiLlama: Polynomial Earn (wind-down announced February 2026)
- Polynomial on X: shutting down Polynomial Chain and Polynomial Trade (February 13, 2026)
- Derive: Lyra is now Derive (August 2024)
- Bankless: Derive V3 goes live, moving on-chain options custody to Ethereum
Educational content, not financial advice. DeFi carries risk, including total loss of funds.