What Is Decentralized Insurance? How DeFi Cover Works in 2026
On this page
What is decentralized insurance?
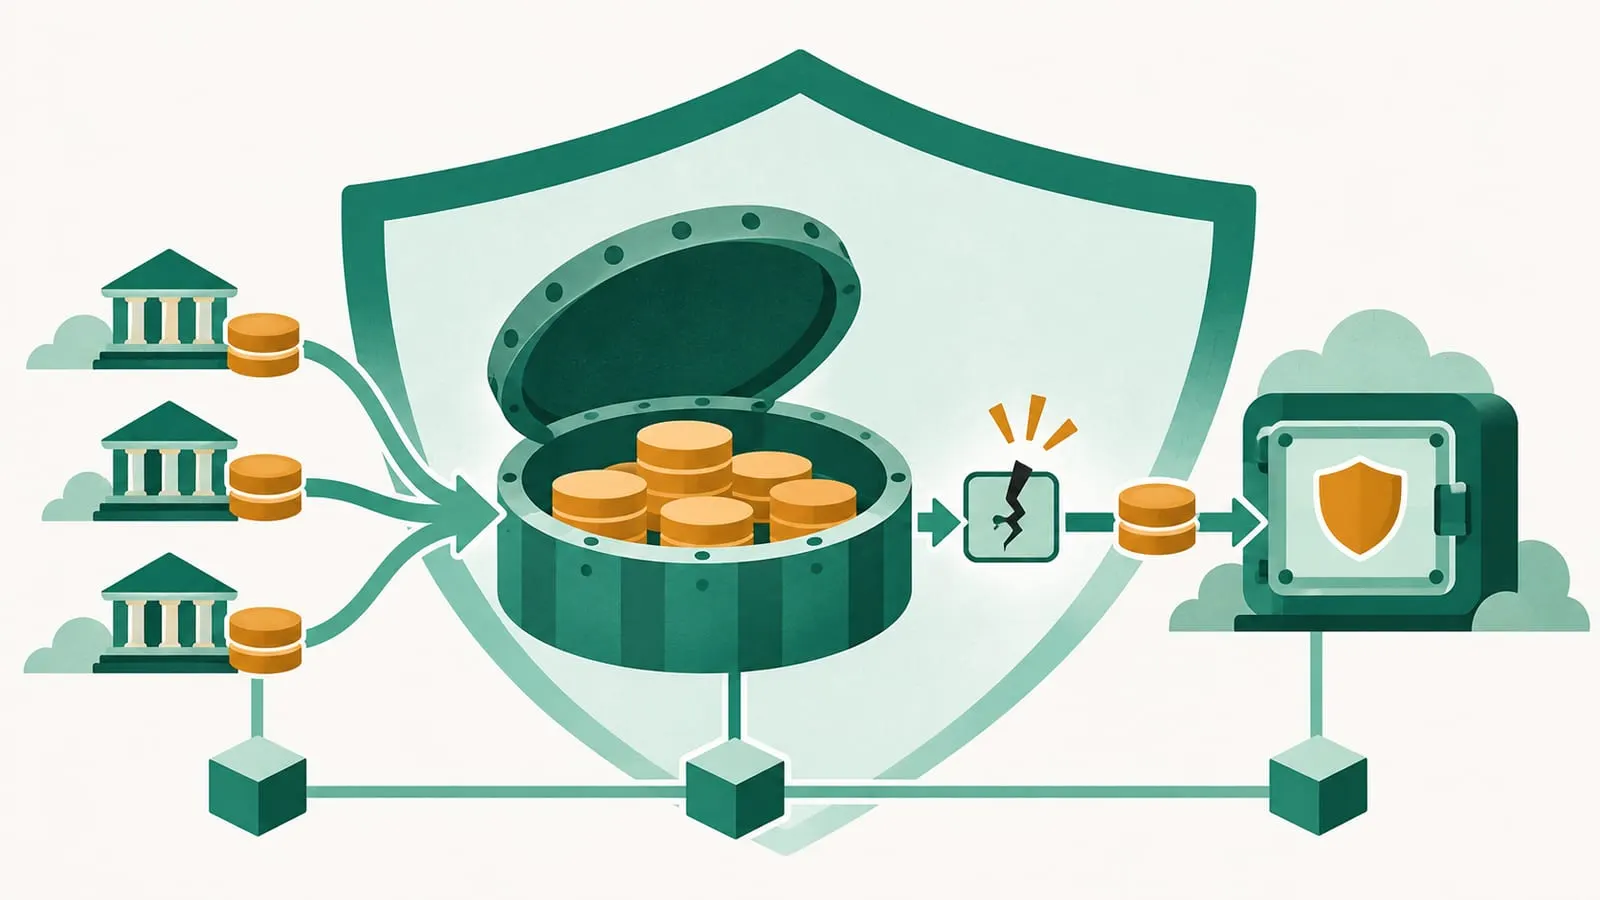
Decentralized insurance is a way to protect crypto positions against specific losses, such as a smart contract hack or a stablecoin losing its peg, using capital pooled on a blockchain instead of an insurance company’s balance sheet. You pay a premium for “cover” on a protocol or risk, other users stake capital to back that cover and earn the premiums, and if a covered event happens, claims are paid from the pool.
Most providers avoid the word “insurance” in their legal terms and call their product “cover”, because it is not a regulated insurance contract. That distinction matters when you need to make a claim.
How decentralized insurance works
- Underwriters supply capital. Users deposit or stake assets into a capital pool or into risk-specific staking pools. In return they earn a share of premiums and sometimes token rewards.
- Buyers purchase cover. You choose a protocol or risk, an amount and a period (often 30 to 365 days), and pay a premium quoted as an annual percentage of the amount covered.
- A covered event happens. For example, a lending protocol you use is exploited and your deposit is lost.
- You file a claim with evidence of your loss, usually proof that you held the position at the time.
- The claim is assessed under the cover wording, by token-holder vote, an expert committee or an independent assessor, depending on the protocol.
- The payout comes from the pool, and underwriters who backed that risk absorb the loss.
Some products are parametric: they pay automatically when an objective trigger is met, such as a flight delay recorded by a data feed or a stablecoin trading below a set price for a set time. Parametric cover removes much of the claims dispute risk but pays a fixed amount whether or not your actual loss matches it.
What does DeFi cover protect against?
| Cover type | What it is meant to pay for | Typical exclusions |
|---|---|---|
| Protocol / smart contract cover | Loss of deposited funds from an exploit of a listed protocol’s code | Phishing, your own compromised keys, front-end attacks, market losses |
| Stablecoin depeg cover | A stablecoin trading below a defined price for a defined period | Short wicks, losses sold before the trigger |
| Custody cover | A centralized exchange or custodian halting withdrawals or being hacked | Voluntary deposits after the event, KYC-related freezes |
| Vault / yield cover | Losses in a specific vault strategy, including underlying protocol failure | Strategy losses that are not caused by a covered event |
| Protocol-purchased cover | A protocol or its auditor covering its own users or bug bounty | Code outside the audited scope |
Always read the cover wording itself. Whether you are paid depends on the exact definitions, not on the product name.
Decentralized insurance platforms in 2026
The market has consolidated sharply since 2022. As of November 2026, DefiLlama tracks about $77 million in Nexus Mutual and roughly $71 billion in total DeFi TVL, so only a tiny share of DeFi deposits is covered.
| Platform | Status (Nov 2026) | How it works |
|---|---|---|
| Nexus Mutual | Active, the largest by capital | Ethereum-based discretionary mutual. Members (KYC required) buy cover and stake NXM to underwrite risk. Cover includes protocol, depeg, custody, fund portfolio and vault products. Claims are decided by a three-member Claims Committee (2 of 3 votes approve). |
| OpenCover | Active | A cover platform built on Nexus Mutual capacity. Its “Covered Vaults”, launched in April 2026 with partners including Morpho, Kiln and Symbiotic, bundle cover into vault deposits. |
| Sherlock | Active, protocol-facing | An audit platform whose “Sherlock Shield” offers exploit payout coverage for audited code it approves, sized by the audit findings. Users do not buy it directly. |
| Firelight | Active (on Flare) | Staked FXRP backs cover against defined protocol failures; its first cover products went live in October 2026, with events reviewed by an independent risk consortium before payout. |
| Ensuro | Active | Supplies on-chain capital to insurance programs, often parametric ones, that partners sell. |
| Etherisc | Status not confirmed (Nov 2026) | Built parametric products such as flight delay and crop cover; product availability has varied over time and we could not confirm which products are currently on sale, so check its site directly. |
| InsurAce, Unslashed, Bridge Mutual, InsureDAO, Nsure | Listed by DefiLlama with dead or retired sites | First-generation cover protocols that no longer appear to be operating. Do not buy “cover” from sites using these names. |
None of these are recommendations. Before using any provider, check its current capital, claim history and whether you are eligible in your country.
Nexus Mutual in more detail
Nexus Mutual launched in 2019 and is a discretionary mutual: members pool capital, and claims are paid at the mutual’s discretion under its rules rather than as a contractual right. To join you must pass identity verification, pay a one-time membership fee (0.002 ETH at the time of writing) and accept the member agreement, and residents of 27 listed jurisdictions, including China, India, Japan, Mexico and Russia, cannot join.
Two changes are worth knowing if you read older guides:
- Claims assessment. Older explainers say NXM holders vote on claims. From March 2023 to November 2025, members staked NXM and a stake-weighted majority decided claims. After a member vote (NMPIP-261), a three-person Claims Committee replaced that system in November 2025; a claim is approved when two of the three assessors accept it within a 72-hour window.
- Distribution. Many users now buy Nexus cover through partners such as OpenCover, whose terms can require identity verification (KYC) when you submit a claim.
After FTX halted withdrawals in November 2022, Nexus paid custody cover claims to members; its claims-history page records 27 claims filed, 24 approved and 3 denied, with a total of $4,924,887.90 paid out. It was one of the clearest tests of on-chain cover so far.
Why decentralized insurance matters, and why it stays small
Hacks remain common. Nexus Mutual’s Q2 2026 review puts 2025 crypto hack losses at about $3.4 billion, including the $1.5 billion Bybit exchange hack. Cover lets users transfer some of that risk to people willing to underwrite it, and well-priced cover can act as a market signal of how risky a protocol is.
It stays small for structural reasons:
- Correlated risk. One large exploit can hit many cover buyers at once, which a small pool may not survive.
- Limited capacity. Each protocol can only be covered up to what underwriters are willing to stake.
- Cost vs. yield. A premium of a few percent a year can consume most of a stablecoin yield.
- Trust in claims. Early token-vote models created conflicts of interest, since voters were also the ones paying claims.
- Failures of providers themselves. Several 2021-era protocols wound down, which is exactly the counterparty risk cover is meant to remove.
Risks and limits of decentralized cover
- No deposit protection. This is not a government-backed scheme or a regulated policy, and there is usually no ombudsman to appeal to.
- Claim denial. Your loss may fall outside the wording, for example a phishing drain or an oracle failure that is not defined as a hack.
- Insufficient capital. If claims exceed the pool, payouts may be reduced.
- Smart contract risk in the insurer itself, plus governance and token-price risk for NXM-style models.
- Underwriter losses. If you provide capital, you can lose a large share of it in a single event.
- Eligibility and KYC. You may need to verify your identity, and some countries are excluded.
- Fake insurance sites. Scammers clone cover sites or advertise “insurance” that drains your wallet. Use only official links.
How to decide whether to buy cover
- Size the position. Cover makes most sense for large, long-term deposits in a single protocol.
- Read the wording for what counts as a covered event, the claim window and the proof required.
- Check capacity and capital on the provider’s dashboard and on DefiLlama.
- Compare cost to yield. If the premium wipes out most of the return, the position may not be worth holding.
- Diversify anyway. Cover reduces, but does not remove, the risk of a total loss.
Related reading
Frequently asked questions
Is decentralized insurance legally enforceable?
Generally not like a regulated insurance policy. Nexus Mutual, for example, offers discretionary cover, meaning members have no contractual right to a payout and claims are decided under the mutual's rules.
What does smart contract cover pay for?
It typically pays when a listed protocol suffers a code exploit that causes a material loss of your deposited funds, as defined in the cover wording. It usually excludes losses from phishing, your own key compromise, and normal market price falls.
How much does DeFi cover cost?
Prices are quoted as an annual percentage of the amount covered and vary by protocol, risk and capacity. Check the live quote on the provider's site, and compare it with the yield you expect to earn.
Can I earn yield by providing decentralized insurance?
Yes. Underwriters stake capital that backs cover and earn a share of premiums, but they absorb losses when claims are paid, so the capital can be cut sharply after a large hack.
Is decentralized insurance the same as crypto custody insurance?
No. Exchanges and custodians may buy policies from regulated insurers to cover their own losses. Decentralized cover is something individual users buy, on-chain, for their own positions.
Sources
- DefiLlama: Insurance category
- Nexus Mutual docs: Membership
- Nexus Mutual docs: Claims assessment
- Nexus Mutual docs: FTX halted withdrawals claims (Nov 2022)
- Nexus Mutual: DeFi Insurance Is Dead: Long Live DeFi Insurance (2026)
- Nexus Mutual: The State of Crypto Insurance, Q2 2026
- Nexus Mutual: OpenCover's Covered Vaults
- Firelight: official site (Firelight Cover live; Firelight Risk Consortium)
- Sherlock docs: Sherlock Shield
- Cointelegraph: InsurAce says it will pay millions to claimants after Terra's collapse
Educational content, not financial advice. DeFi carries risk, including total loss of funds.
Answers about Decentralized insurance
- Here's Why Stablecoins Should Be FDIC Insured
Currently, stablecoins are not FDIC insured. Read this article to discover the many reasons that stablecoins should be FDIC insured.
Community questions about Decentralized insurance
- Is decentralized insurance the next big DeFi trend?
Decentralized insurance is the next big DeFi trend since insecurity is a significant DeFi threat. DeFi insurance protocols provide insurance products and…