DeFi Arbitrage: How It Works, Common Strategies and the Risks
On this page
The short answer
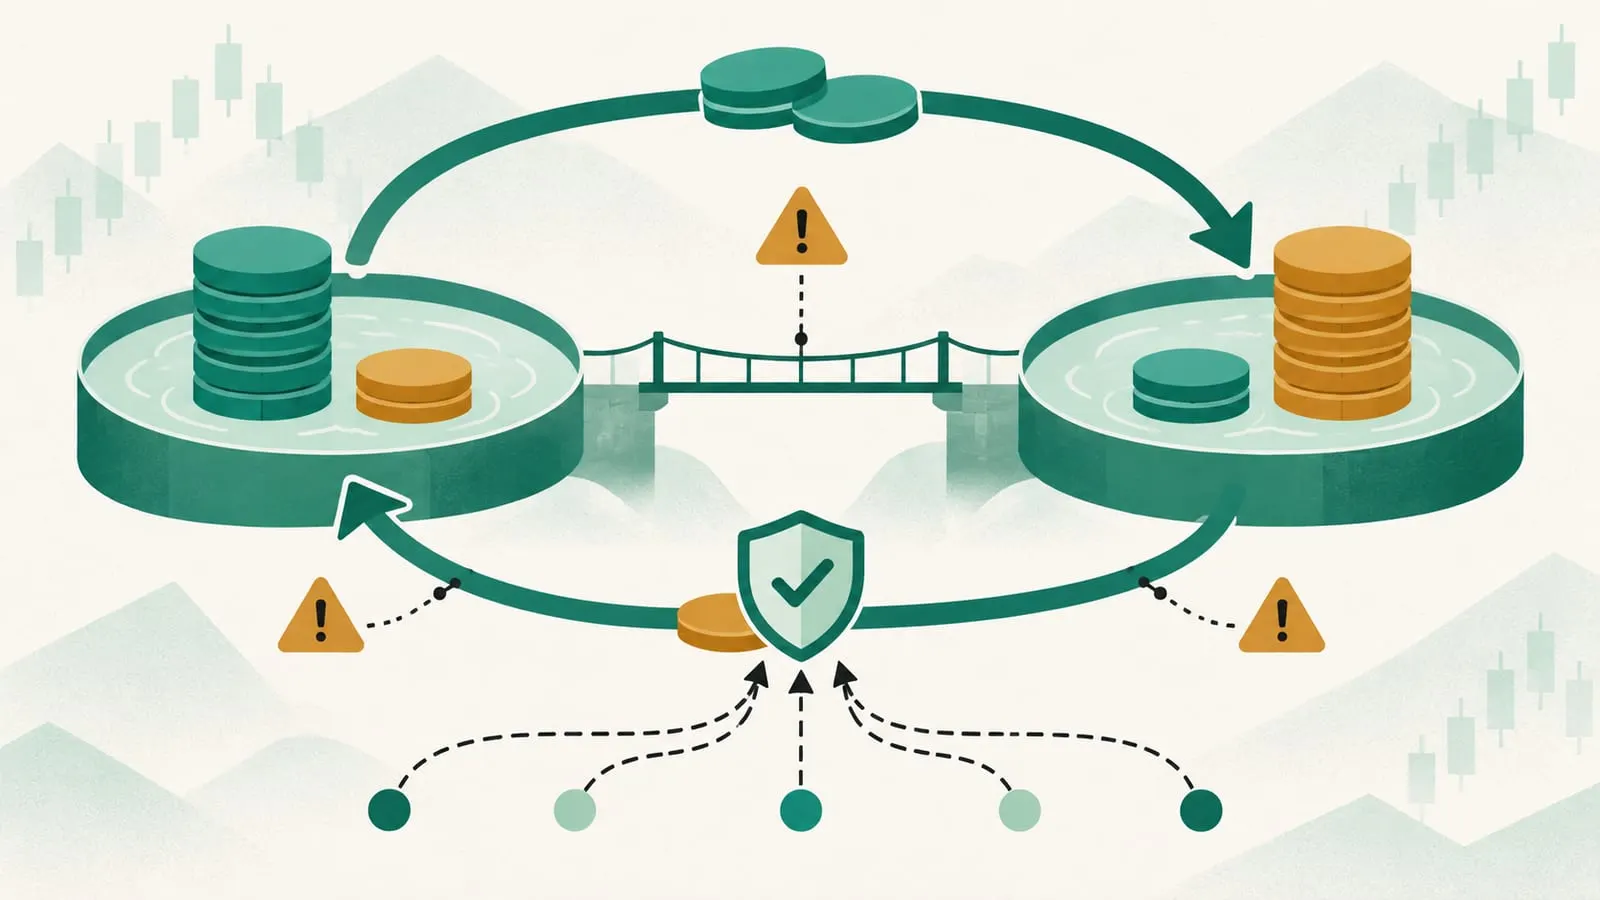
DeFi arbitrage is buying a token where it is cheaper and selling it where it is more expensive, across decentralized exchanges, blockchains, or between a centralized exchange and a DEX. It keeps prices aligned across markets and is a large, legitimate part of on-chain trading.
It is often sold as a sure profit, but that is only true on paper. In practice, the risks of DeFi arbitrage are execution failure, losing the race to faster bots, gas costs, slippage, smart contract bugs, front-running, bridge and exchange risk, and outright scams. Most simple opportunities are captured by professional searchers within the same block. This page explains how arbitrage works, the main strategies and each risk in detail. It is educational, not trading advice.
How DeFi arbitrage works
Automated market makers (AMMs) such as Uniswap and Curve do not look at outside prices. A pool’s price only changes when someone trades against it. When ETH rises on a big centralized exchange, an ETH/USDC pool still quotes the old, lower price until an arbitrageur buys ETH from the pool and pushes its price up to match. Every large trade on one DEX also moves that pool’s price away from other pools, creating a gap someone can close.
A real example cited in ethereum.org’s MEV documentation: a searcher spotted ETH/DAI priced differently on Uniswap and Sushiswap, bought on the cheaper one and sold on the more expensive one in a single transaction, turning 1,000 ETH into 1,045 ETH. Because both legs are in one transaction, it is atomic: either everything executes or nothing does.
Arbitrage profit is not free money from nowhere. Research on “loss-versus-rebalancing” shows it comes largely out of liquidity providers, who sell to arbitrageurs at stale prices. That is one reason LP returns can disappoint (see impermanent loss).
Common DeFi arbitrage strategies
| Strategy | How it works | Atomic? | Key extra risk |
|---|---|---|---|
| DEX-to-DEX (spatial) | Buy on one DEX, sell on another, same chain | Yes | Competition, gas |
| Triangular | Trade A to B to C back to A across pools when the loop prices are inconsistent | Yes | Competition, slippage across three legs |
| CEX-DEX | Trade the DEX toward a centralized exchange price, hedge on the CEX | No | Inventory and exchange counterparty risk |
| Cross-chain | Buy on one chain, sell on another | No | Bridge delays, bridge exploits, price moves |
| Flash-loan arbitrage | Borrow without collateral, arbitrage, repay in one transaction | Yes | Contract bugs, failed attempts |
| Liquidations | Repay an under-collateralised loan to collect a bonus | Yes | Competition, oracle timing |
| Stablecoin peg arbitrage | Buy a stablecoin below $1, redeem or sell at $1 | Often no | Depeg not recovering, redemption limits |
| Rate arbitrage | Borrow where rates are low, lend where they are high | No | Rate changes, liquidation |
Flash loans
A flash loan lets a smart contract borrow assets with no collateral, provided it repays them plus a fee within the same transaction. If it cannot repay, the whole transaction reverts. Aave V3’s flash loan fee was set at 0.05% at deployment and can be changed by governance. Flash loans let anyone arbitrage with large size, which is why opportunities are captured so fast, and they are also a common tool in price-manipulation exploits. For background, see what a flash loan is.
Arbitrage and MEV
Most on-chain arbitrage today is part of maximal extractable value (MEV): profit from choosing which transactions go into a block and in what order. Specialised “searchers” run bots that watch the mempool and new blocks, then send transaction bundles to block builders, often through systems such as MEV-Boost. To win a contested opportunity they bid away most of the profit as fees to builders and validators. ethereum.org describes DEX arbitrage as the simplest and most well-known MEV opportunity, which is exactly why it is so contested. For how this affects liquidity providers, see what MEV does to liquidity mining.
The risks of DeFi arbitrage
1. Competition and latency
Simple price gaps on public blockchains are visible to everyone. Professional searchers co-locate infrastructure, receive private order flow and pay builders for priority. A trader spotting a gap on a dashboard and clicking “swap” will almost always arrive after the gap has closed.
2. Execution and failed-transaction costs
On many chains you pay gas even if your transaction reverts or arrives too late. Bots that compete in public gas auctions can burn more on failures than they earn. Private submission routes such as Flashbots Protect only include a transaction if it will not revert, so users do not pay for failed transactions there, but you can still lose the opportunity.
3. Slippage and price impact
A quoted price gap shrinks as you trade into it. If the pools are shallow, your own trade can erase the profit, and a loose slippage tolerance can turn a small expected gain into a loss. See slippage and how to calculate it.
4. Front-running and sandwich attacks
A visible profitable transaction in the public mempool can be copied by “generalized front-runners” with a higher fee, or a large swap can be sandwiched: a bot buys just before you and sells just after. Private transaction submission reduces this exposure.
5. Smart contract risk
Arbitrage contracts, especially ones using flash loans, are custom code holding or routing funds. Bugs in your own contract, approvals left open, or interaction with a malicious or exploited token can lose funds. Arbitrage bots themselves are targets: in April 2023, two brothers allegedly exploited other MEV bots for about $25 million in roughly 12 seconds. They were charged in the US in 2024 and deny wrongdoing; their trial ended in a mistrial in November 2025 after the jury deadlocked. Prosecutors sought a retrial. As of the latest court filings and reports we could find (a March 30, 2026 joint letter in United States v. Peraire-Bueno, No. 1:24-cr-00293, S.D.N.Y.), the judge had not ruled on the defence’s motion for acquittal, no retrial date had been set, and the defence had asked that any retrial take place between June and September 2027. The protocols you route through can also be hacked mid-trade.
6. Inventory and price risk
Non-atomic strategies, such as CEX-DEX and cross-chain arbitrage, require holding assets on more than one venue. Prices can move while you wait for a block, a bridge or a deposit confirmation, turning an arbitrage into an ordinary directional bet.
7. Bridge, exchange and counterparty risk
Cross-chain arbitrage depends on bridges, which have been among the largest sources of crypto losses, and CEX-DEX arbitrage depends on the exchange staying solvent and processing withdrawals. A frozen withdrawal or a bridge exploit can trap the capital you need. See counterparty risk.
8. Oracle and depeg risk
Peg arbitrage, buying a stablecoin at $0.97 expecting it to return to $1, only works if it does return. Depegs can deepen instead, and redemption at par may be limited to approved institutions.
9. Scams posing as arbitrage
This is the biggest practical risk for individuals. Videos and posts advertise “MEV arbitrage bots” that you deploy yourself: copy some code into Remix, fund the contract with ETH and press start. Security firm SentinelLABS documented such contracts in 2025, promoted through aged YouTube accounts, where hidden logic sends the deposited funds to the scammer; the most successful wallet it traced had collected about 245 ETH, worth more than $900,000 at the time. Red flags:
- Promises of daily or guaranteed returns from a “bot”.
- Instructions to deploy a contract you cannot read, or obfuscated code.
- A minimum deposit, usually in ETH, before the bot “starts”.
- Comment sections full of praise and disabled criticism.
See our bots glossary entry and scams hub for more warning signs.
10. Legal and tax risk
Arbitrage is legal, but the line between arbitrage and market manipulation, or exploiting a protocol’s bug, can be contested, and prosecutors have brought cases. Every trade may also be a taxable event, which matters for high-frequency strategies.
How people find DeFi arbitrage opportunities
- Price comparison across DEX aggregators and charting tools, which mostly shows that gaps are small and short-lived.
- Running a node and a searcher bot that simulates trades against current pool states and submits bundles privately.
- Monitoring lending markets for positions close to liquidation.
- Watching stablecoin and liquid staking token pegs for discounts, while weighing why the discount exists.
Realistically, competitive on-chain arbitrage is an engineering business. If you are interested in earning from DeFi without competing against bots, lower-intensity options are covered in our yield farming strategies guide, with their own risks in risks of yield farming.
Arbitrage vs other DeFi trading
| Arbitrage | Directional trading | Market making / LP | |
|---|---|---|---|
| Profit source | Price gaps between venues | Price going up or down | Fees from traders |
| Main risk | Losing the race, execution, scams | Price moves against you | Impermanent loss, arbitrage losses |
| Skill required | Engineering and infrastructure | Market judgement | Range and risk management |
For more on derivatives and trading strategies, browse Trading, Derivatives & Options.
Frequently asked questions
What are the risks of DeFi arbitrage?
The main ones are being beaten to the trade by faster bots, paying gas for failed or unprofitable transactions, slippage that erases the price gap, smart contract bugs in your own or a protocol's code, front-running and sandwich attacks, bridge or exchange failure on cross-venue trades, holding inventory while prices move, and falling for fake arbitrage-bot scams.
Is DeFi arbitrage still profitable?
For professional searchers with low-latency infrastructure, private order flow and capital, yes, though competition squeezes margins. For individuals trading manually, simple DEX-to-DEX gaps are almost always taken by bots first, and most of the profit ends up paid to block builders and validators.
Is DeFi arbitrage guaranteed profit?
No. Atomic arbitrage inside one transaction removes price risk between the legs, but you still pay for failed attempts, can lose to competitors, and are exposed to code bugs. Cross-chain and CEX-DEX arbitrage add inventory, bridge and counterparty risk.
How do flash loans work in arbitrage?
A flash loan lets you borrow assets with no collateral as long as you repay them plus a fee in the same transaction. If the arbitrage does not produce enough to repay, the whole transaction reverts. Aave V3's flash loan fee was set at 0.05% at deployment and can be changed by governance.
Are arbitrage bots legit?
Real arbitrage bots exist, but they are private, custom-built and constantly updated. Bots marketed to the public with promises of daily profits, especially ones that ask you to deploy a contract and fund it, are typically scams designed to send your ETH to the creator.
Sources
- ethereum.org: Maximal extractable value (MEV)
- Aave V3 documentation: Flash loans
- Flashbots documentation: Flashbots Protect overview
- Milionis et al.: Automated Market Making and Loss-Versus-Rebalancing (arXiv)
- SentinelLABS: Ethereum drainers pose as trading bots to steal crypto
- The Block: Mistrial declared for 'MEV brothers' accused of $25 million fraud on Ethereum
- DL News: MEV brothers seek acquittal before any retrial (March 2026)
- CourtListener: United States v. Peraire-Bueno, 1:24-cr-00293 (S.D.N.Y.) docket
- Inner City Press: joint letter on retrial timing (March 30, 2026)
- Cointelegraph: Fake trading bots on YouTube drain over 256 ETH (SentinelLABS findings)
Educational content, not financial advice. DeFi carries risk, including total loss of funds.